17 Sep 2026
Before The Bank Sends That Notice: A Debt Restructuring Roadmap For Indian Promoters, SME Owners And CFOs
Introduction
If you've landed here, your loan account probably isn't in great shape right now. Maybe it's sitting at SMA-1. Maybe you've already crossed into SMA-2 and the bank's relationship manager the one who was calling every other week a year ago has gone noticeably quiet.
Here's what you need to hear before anything else: debt restructuring isn't a white flag. It isn't something that only happens to businesses that failed. It's a recognised, RBI-backed mechanism that exists precisely because even solid businesses hit rough patches and because banks, despite how things sometimes feel from the other side of that desk, don't actually want your loan to turn NPA either.
The businesses that come out of financial stress with the least damage aren't the ones with the fewest problems. They're the ones that stopped waiting and started moving. If you're reading this, you still have options. How many, and how good that depends almost entirely on what you do in the next few weeks.
The Short Version, For Those Who Don't Have Time Right Now
Debt restructuring is when you and your lender formally rework the loan terms the repayment timeline, the interest, the EMI structure, sometimes the outstanding principal itself so repayment actually reflects where your business stands today. It's available to SMA-classified accounts and, in many cases, to NPA accounts too. The earlier you engage, the more leverage you hold and the better the terms you can negotiate.
The 90-Day Window You're Burning Through Without Realising It
Here's what most promoters don't understand until it's too late: the clock starts the moment your account shows overdue amounts. It doesn't pause while you wait for collections or debate the next move internally.
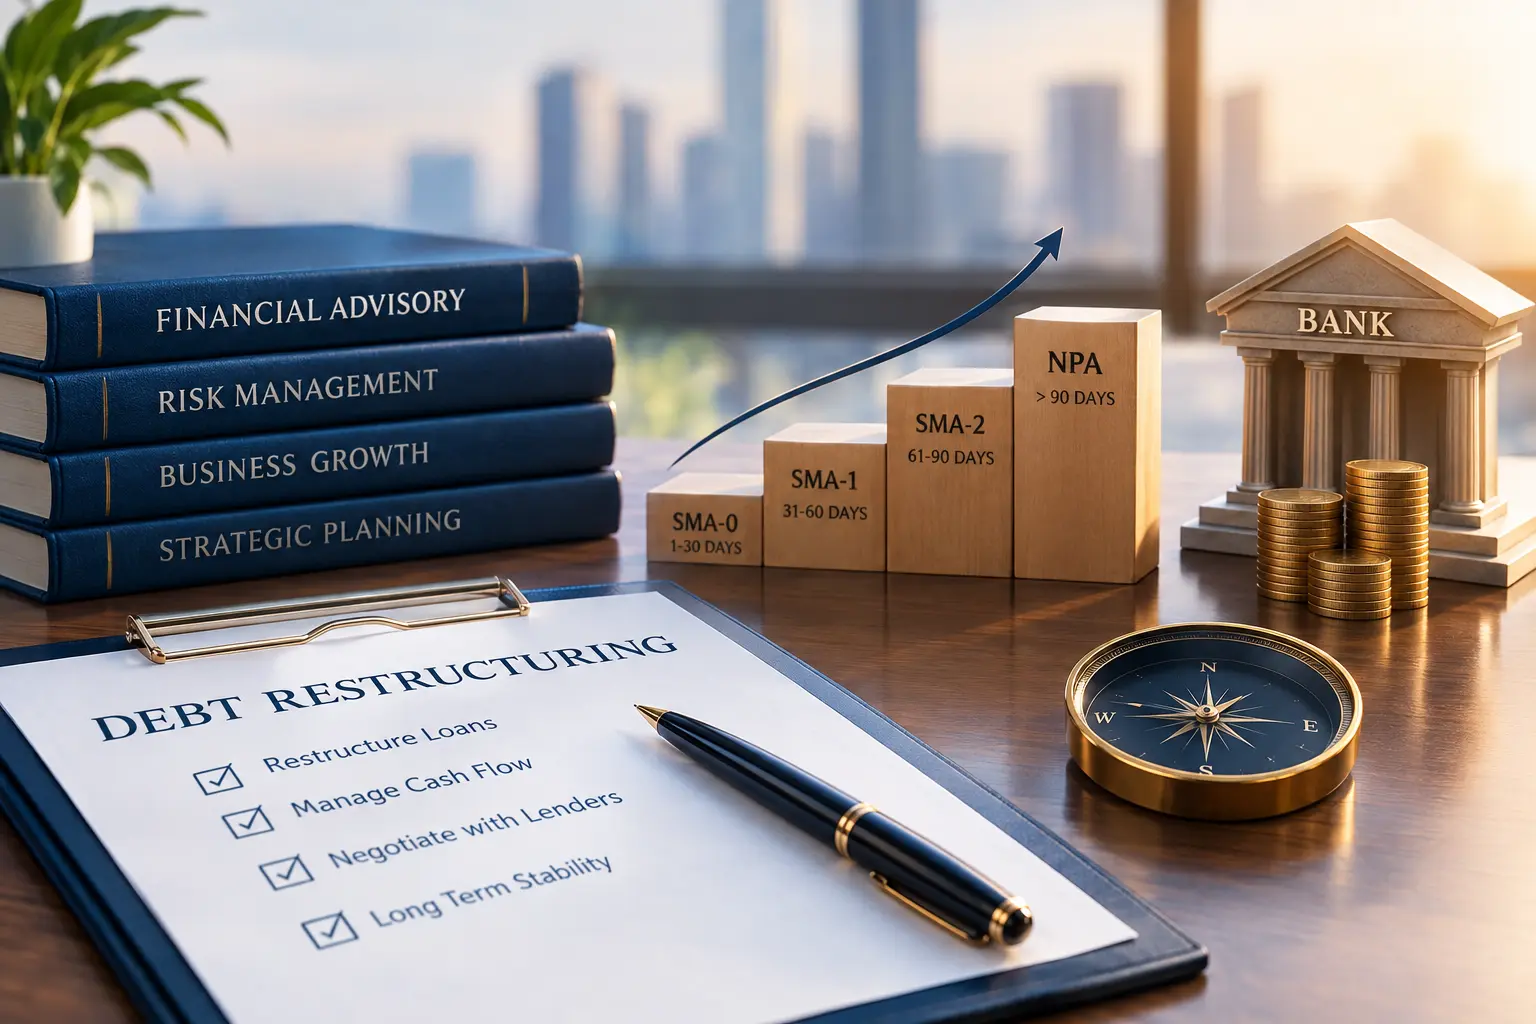
Banks classify stressed accounts under the Special Mention Account (SMA) framework in three stages. SMA-0 is 1 to 30 days overdue. SMA-1 is 31 to 60 days. SMA-2 is 61 to 90 days. Cross the 90-day mark without a resolution in place and you're officially an NPA at which point the bank's enforcement machinery engages, CRILC flags go live (CRILC being the Reserve Bank's Central Repository of Information on Large Credits, visible to every lender in your consortium), and documentation begins that takes months to reverse even if your business recovers completely.
Within this 90-day corridor, things work differently. A borrower who comes forward with a concrete plan not explanations, a plan can still have a direct bilateral conversation about modified terms before enforcement enters the picture. The bank hasn't yet moved into recovery mode. Whatever remains of the relationship still works.
Most promoters waste this window expecting the situation to self-correct. The big receivable takes another 45 days. The internal cash flow forecast keeps getting revised. The bank, meanwhile, is documenting quietly. A promoter who walks into that lender meeting during the SMA stage isn't arriving as a defaulter. They're arriving as someone solving a shared problem and that framing, more than anything else, changes what gets offered on the other side of the table.
What Debt Restructuring in India Actually Looks Like in Practice
Forget the regulatory definition for a moment. In practice, debt restructuring comes down to one question you need to answer for your lender: given where things genuinely stand, what repayment structure can this business sustain and honour?
That answer takes different forms depending on the situation. Sometimes it's extending the tenure so your monthly obligation drops to something the business can actually service from current cash flows. Sometimes it's converting your working capital loan into a term loan one of the most commonly used restructuring tools in India which transforms short-term pressure into a structured repayment spread across three to seven years. Sometimes a moratorium of three to twelve months is what's needed to stabilise operations before repayment resumes. Accumulated unpaid interest can be converted into a Funded Interest Term Loan (FITL) a separate facility with its own repayment schedule so it stops compounding into something unreachable. Penal interest and overdue charges are often waived as part of the package to bring the outstanding figure to a level the bank can realistically recover.
No two restructuring packages are identical. The right combination depends on your loan structure, the lender's internal framework, the nature of the stress, and the quality of what you put on the table.
Financial Restructuring vs. Debt Restructuring — These Are Not the Same Thing
They get used interchangeably in most conversations, which creates real confusion when you're trying to decide what you actually need and who to speak to.
Debt restructuring is specific to your loan obligations. It's a lender-borrower negotiation about modifying what you owe and how you'll repay it.
Financial restructuring is the broader picture. It can include debt restructuring as one part, but it also covers equity restructuring, ownership changes, fresh capital infusion, monetisation of non-core assets, and sometimes operational changes. A corporate borrower carrying stress across multiple banks, NBFCs, and bond holders with a capital structure that needs overhaul across all of it that's a financial restructuring exercise, not just a loan renegotiation.
For most MSME borrowers with a single lender and a contained quantum of debt, targeted debt restructuring is the faster, more focused path. For larger corporates with fragmented consortiums and complex balance sheets, the full financial restructuring exercise becomes necessary. Knowing which situation you're actually in before you start the process saves months.
What the Bank Is Actually Hoping You'll Do Next
Most promoters walk into restructuring conversations assuming they're going to beg. The real dynamic is more interesting and significantly more in your favour than that.
When a loan turns NPA, banks are required under RBI's prudential norms to provision against it setting aside capital that earns nothing and strains the balance sheet. Provisioning starts at 15% for secured sub-standard accounts and scales to 100% for loss assets. That's real money locked up, earning nothing. For public sector banks with NPA targets to manage and capital adequacy ratios to protect, a structured resolution is genuinely preferable to the slow, expensive grind of SARFAESI proceedings or IBC litigation both of which typically recover less than a negotiated bilateral arrangement would have produced.
Which means you're not walking in to ask for mercy. You're arriving with a commercially rational solution to a problem the bank also has. But and this is non-negotiable you have to arrive with honest numbers and a clear narrative. Any indication of fund diversion, financial misrepresentation, or inconsistencies between what your CA's records show and what you're presenting ends the conversation immediately. Banks have reviewed hundreds of stressed cases. Credibility, built on accurate financials and a straight account of what went wrong, is your most valuable asset in that room.
When the IBC Enters the Picture And Why You Don't Want It To
The Insolvency and Bankruptcy Code (IBC) exists for situations where bilateral restructuring has genuinely run out of road fragmented lender groups, very large outstanding amounts, disputes that can't be resolved between parties. Under the Corporate Insolvency Resolution Process (CIRP), an insolvency professional takes interim management control and lenders vote as a Committee of Creditors on resolution plans submitted by prospective buyers or investors.
It has worked for some very complex Indian corporate cases. But for the promoter of a business that's under stress and still operational, the IBC is a last resort not a first option. Management control transfers. The process is public. Your equity position typically suffers severely. The statutory 330-day outer limit regularly extends in practice.
Structured debt restructuring done early is almost always the better outcome. The IBC is what happens when that window closes.
The Three Things That Actually Derail Good Restructuring Cases
Waiting. Nothing compresses your options faster. Every week inside the SMA window is a week of negotiating leverage you're voluntarily giving up.
Walking in unprepared. A credit committee is a formal review, not a conversation. Arriving without current financials, a realistic cash flow projection, and a coherent account of what caused the stress tells everyone in that room that you haven't actually engaged with the problem. Well-documented proposals move forward. Verbal assurances don't.
Trying to handle it without specialist support. Multi-lender coordination, credit policy navigation, internal bank documentation requirements this is specialist territory. For businesses facing complex loan stress, understanding the role of a financial advisor for debt can help promoters and CFOs prepare for lender negotiations, restructuring discussions and resolution planning. An experienced advisory firm doesn't just write the proposal better. It gets it to the right decision-makers inside the institution, which frequently matters more than the document itself.
If your account is currently showing stress, explore what distressed account funding options look like alongside a restructuring plan, or review the scope of stressed account advisory services available before things deteriorate further. For MSME-specific resolution frameworks and support schemes, SIDBI's official guidance is a useful reference. For regulatory and legal analysis on restructuring and IBC proceedings, Mondaq India's financial services coverage is relied upon by banking professionals and lawyers across the country.
Frequently Asked Questions
Q1 What exactly is debt restructuring and is it different from just missing an EMI?
Missing an EMI is a default event. It triggers SMA classification and starts the bank's internal documentation process. Debt restructuring is the opposite: you're getting ahead of the default, or addressing it formally, by proposing revised loan terms that both sides can work with. One is a problem happening to you. The other is a move you're making. That distinction matters enormously in how lenders respond.
Q2 Between debt restructuring and financial restructuring which one does my situation actually call for?
Think of it this way. Debt restructuring is about what you owe your lenders and how that gets repaid. Financial restructuring looks at the whole business the equity, the ownership, the assets, the operations, and the debt, all together. If you've got one bank, a manageable loan, and the rest of the business is intact, you're looking at debt restructuring. If you have debt spread across five lenders, a balance sheet that needs structural work, and possibly new capital coming in, that's financial restructuring. The two can overlap, but starting with the wrong frame wastes time.
Q3 Will debt restructuring hurt my CIBIL or credit profile?
Honestly, yes it will leave a mark. Restructured accounts are reported to credit bureaus and can affect how future lenders view your file. But here's the comparison that matters: a full NPA classification does more damage. A SARFAESI enforcement action does more damage. An IBC proceeding does the most of all. If you're choosing between a restructuring flag and a spiral into NPA recovery proceedings, restructuring is the significantly less costly path and most informed lenders, looking at your profile later, will read the context.
Q4 How long does the process take from proposal to approval?
It depends on your setup. A single-lender account with a clean, complete submission can move through in roughly 60 to 180 days from proposal to final documentation. Consortium accounts where multiple lenders need to align take longer. Large borrowal accounts may require an Independent Credit Evaluation by an RBI-authorised rating agency, which adds to the timeline. The most reliable way to compress the timeline? Start earlier and submit a complete, well-documented proposal the first time. Revisions and missing documents are the biggest causes of stalling.
Q5 The account has already turned NPA. Is restructuring still on the table?
Yes but the terms and the conversation are different. Post-NPA, you're dealing with the bank's stressed assets or recovery division, not the relationship team. Options include OTS (One Time Settlement), bank-specific revival schemes, or for large accounts, a resolution plan under the IBC framework. What changes is your leverage and the cost of the outcome. The further past NPA classification you go, the more you're working with what the bank is willing to accept rather than negotiating toward what works for you. Everything that can be addressed in the SMA stage should be.
Q6 What do I actually need to bring to the first meeting with the bank?
At minimum: two to three years of audited financials, a cash flow projection for the next two to three years showing the proposed repayment capacity, a written business note explaining what caused the stress and why the business is viable going forward, a full list of existing credit facilities across all lenders, and your collateral documentation. For large borrowal accounts, the bank may require a Techno-Economic Viability (TEV) study by an approved agency. Don't walk in with partial information expecting to fill gaps later incomplete submissions almost always stall, and first impressions in these reviews carry real weight.
Conclusion
Debt restructuring isn't the moment your business failed. For the promoters and CFOs who look back at financial stress periods with the least regret, it's usually the moment they decided the business wasn't going to. The SMA window is real, the tools exist, and the banks however it may feel right now have strong commercial reasons to work with you rather than against you.
But none of that moves without urgency. The window doesn't stay open.
Talk to Credit Curators.
We work exclusively with stressed and distressed loan situations structured advisory, lender negotiation, and the kind of speed these situations actually demand. Start with a confidential conversation. No obligation.
📞 www.creditcurators.in | Follow us on LinkedIn for weekly insights on NPA resolution and debt restructuring across India.
This article is for informational purposes only and does not constitute financial or legal advice. For guidance specific to your situation, consult a qualified financial advisor or legal professional.



 Credit Curators