21 Oct 2026
Early Warning Signs Of Missed Payments Every MSME Owner And CFO Must Recognize Before The Bank Does
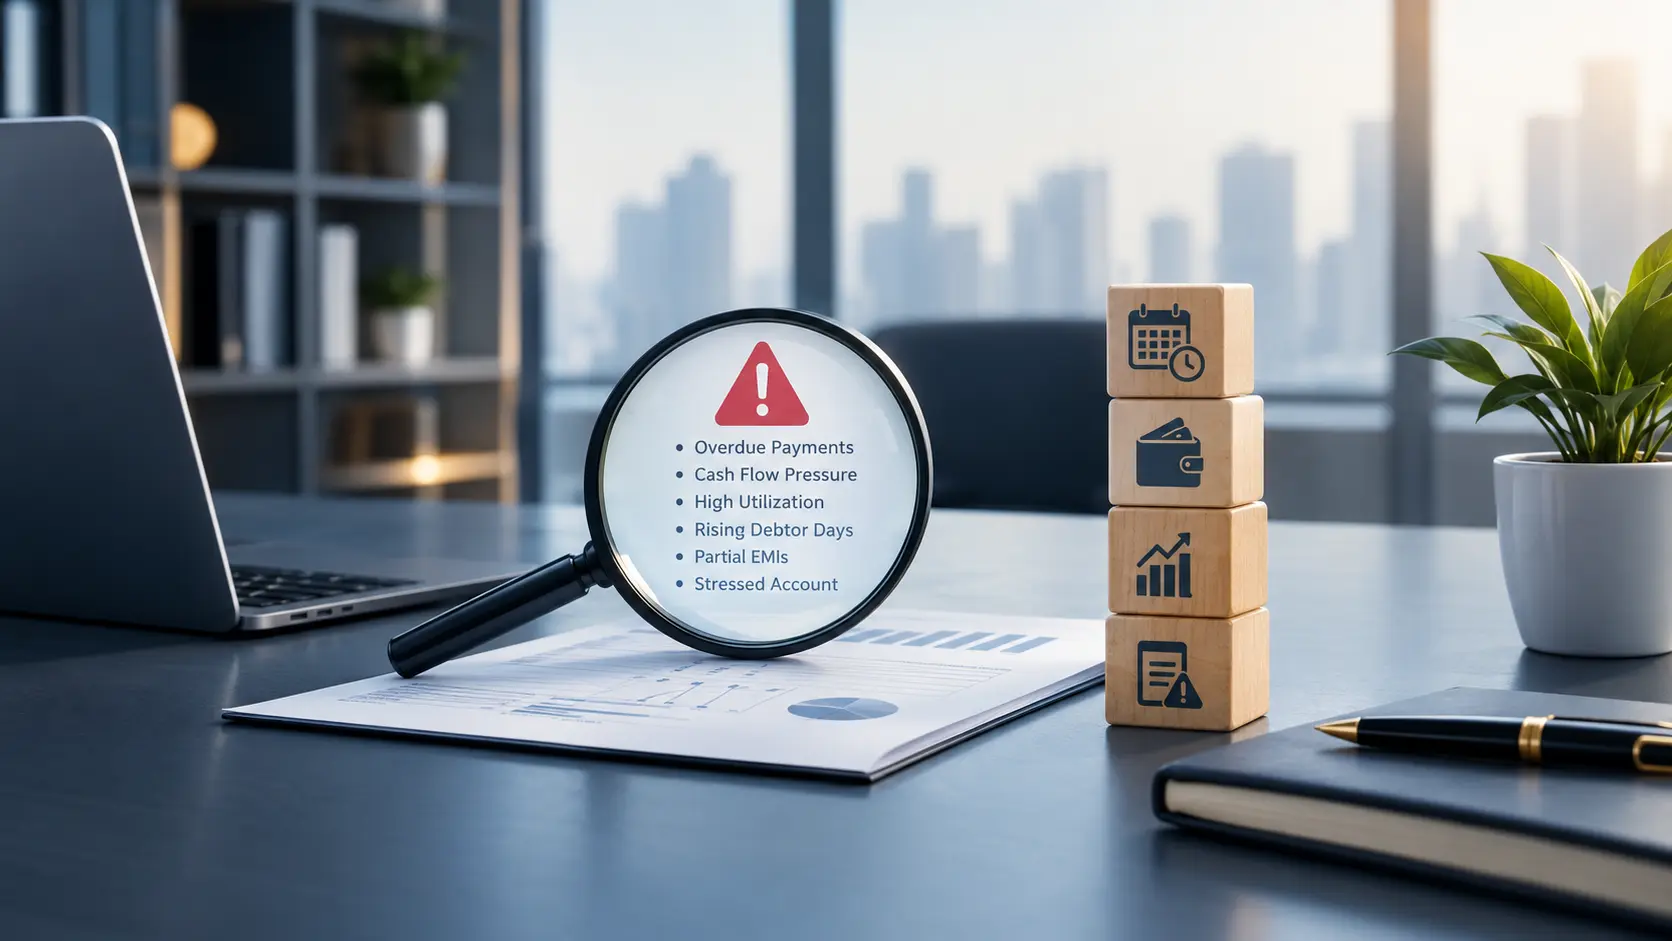
Most loan accounts don't fall into stress overnight. They slip quietly, over weeks, through signals hiding in plain sight inside your own financial data.
Here's what most corporate debt crises have in common: by the time the CFO picks up the phone, the bank has already reclassified the account. The early warning signs of missed payments were there for months: the overdraft that never fully recovered between cycles, the customer stretching 45-day dues to 80, and the EMI that went out three days late and then five. Individually, none of it looked like a crisis. Together, it was a pattern the lender was already reading.
This piece is about reading that pattern before your bank does and acting while you still hold the leverage to shape the outcome. Whether you're an MSME promoter, a CFO managing covenant-heavy debt, or an advisor watching a client's account slide, the signals below are what you need to be tracking.
The most actionable early warning signs of missed payments are behavioral before they're financial. Persistent overdraft pressure, inter-company transfers just before due dates, rising debtor days, and partial EMIs each alone are manageable. Together, they signal a structural cash flow mismatch. Spotting even one early opens a window for restructuring or alternative funding before your account moves into SMA or NPA territory.
Banks Don't Surprise Borrowers. Borrowers Stop Paying Attention
The journey from a standard loan account to NPA isn't sudden. It's a sequence, and every step has a regulatory name. Under RBI's IRAC norms, overdue between 1 and 30 days pushes an account into SMA-0. Between 31 and 60 days, SMA-1. Between 61 and 90 days, SMA-2. Cross 90 days, and the account is formally nonperforming. That's when SARFAESI machinery moves notices under Sections 13(2) and 13(4) begin.
What borrowers typically don't know: their bank wasn't waiting for Day 30. Core banking platforms run behavioral scoring every day, tracking utilization trends, transaction patterns, credit inflows, and repayment timing. Large lenders' EWS frameworks often flag accounts two to four weeks before a formal SMA classification. The notice you receive isn't news to your banker. They've been watching for a while. Knowing this isn't cause for panic. It's caused you to move faster than you otherwise would.
Seven Early Warning Signs of Missed Payments
These are the signals that precede a missed payment and the ones trained lender eyes pick up long before you bring it to them.
Sign 01
Your Cash Credit Limit Is Always Nearly Full
When a ₹2 crore working capital facility consistently sits between ₹1.8 and ₹2 crore with no meaningful reduction between drawdowns, that's not active usage; that's a business staying alive on credit. Your relationship manager knows the difference, and it goes on record.
Sign 02
You're Fund-Hunting in the 10 Days Before Every Due Date
If you're routinely checking balances, holding vendor payments, or waiting on one specific receivable to clear before each EMI, that scramble is harder to hide than the payment itself. The behavioral pattern shows up in transaction data well before any formal overdue flag appears.
Sign 03
Customers Are Paying Later, But Your Bank Isn't Waiting
Debtor days climbing from 45 to 70 without a revenue spike creates a structural mismatch. Your repayment schedule doesn't flex because your largest buyer decided to stretch dues. That gap accumulates quietly for months, then announces itself all at once in the form of a missed payment.
Sign 04
Your Overdraft Is Funding Payroll
A cash credit facility is built for short-term, self-liquidating working capital, not recurring operational expenses. When it's regularly funding salaries, GST dues, or utility bills, the facility has stopped supplementing cash flow and started replacing it. That's a line crossed, and lenders notice the pattern in transaction data.
Sign 05
Partial EMIs Feel Like a Solution
Paying 75% of the EMI and asking your RM for a "small adjustment" feels like managing the relationship. It is being logged as a pattern. Every such instance feeds into the behavioral score your account carries, and a pattern of partial payments is a significant input in early warning assessment.
Sign 06
Group Funds Visit the Borrowing Entity Around Due Dates
Funds routed from a sister concern to service an EMI, then leaving 48 hours later—this is common in MSME group structures and entirely trackable. Lenders with cross-entity EWS monitoring flag it quickly. An entity that needs external rescue every month cannot, by definition, service its own debt.
Sign 07
DSCR Has Quietly Slipped Below 1.0
A Debt Service Coverage Ratio under 1.0 means the business generates less cash than it needs to meet its debt obligations. That number didn't drop overnight; it compressed over two or three quarters of margin pressure, usually visible long before the ratio itself crossed the threshold. Many covenant-based agreements allow lenders to trigger restructuring conversations well before 1.0 is reached.
What the Bank Already Has in Your File
The EWS mandate from RBI covers more than overdue days. Large bank systems flag bounced ECS returns on non-loan accounts, GST turnover mismatches against actual credit inflows, shifts in supplier credit behavior, and promoter-linked entity stress often well before a formal SMA classification is made.
A promoter who believes the problem is "just a temporary liquidity issue" might be surprised to find the account was placed under internal monitoring weeks ago. The most important shift here is recognizing what that means practically: the window between "internally flagged" and "formal SARFAESI notice" is exactly where you have the most room to move, and it shrinks fast once legal timelines begin.
The Window You Have and How Quickly It Closes
From the moment any early warning signs appear, a real window exists. Restructuring under the RBI framework is still possible without a formal NPA classification on your credit history. One-time settlements can be approached before the lender's legal team takes over. Alternative funding, including stressed account funding, can bridge a temporary gap without forcing asset liquidation.
Once NPA status is formally recorded, none of these options disappear; they just get harder, more expensive, and less favorable to the borrower. The first call should happen long before the bank makes its first move. That's not a suggestion. It's the only version of this story that ends well for the borrower.
What to Actually Do When You See These Signs
Diagnose honestly before you act. Bridge funding fixes a temporary cash flow gap. Restructuring addresses a structural mismatch. A formal resolution process handles a deeper business problem. Applying the wrong solution burns time, which is exactly what you don't have.
Call your banker before the bounce. Relationship managers have discretion they cannot use retroactively. A conversation before a missed payment is categorically different from one after. Even a 48-hour head start changes the tone and the outcome.
Build an independent cash flow projection. Your next three to six months of obligations mapped against realistic inflows. That document anchors every restructuring conversation and tells you which version of a solution you actually need.
Explore alternatives in parallel, not sequentially. If the underlying business is sound but the balance sheet is stretched, distressed account funding options exist specifically for accounts at this stage before the NPA clock runs out. Waiting for one path to fail before trying the next costs you the window.
Sources & References
- RBI Prudential Framework for Resolution of Stressed Assets — rbi.org.in
- SIDBI MSME Pulse Report — sidbi.in
- Insolvency and Bankruptcy Board of India (IBBI) — ibbi.gov.in
Frequently Asked Questions
Q1: My loan is overdue by 12 days. Should I be worried, or is this still manageable?
Act now, not when it hits 30. SMA-0 officially starts on Day 1 of overdue, so on Day 12, you're already in it. The good news is SMA-0 is genuinely still manageable territory. What you want to avoid is letting inaction carry you to SMA-2, where the options get meaningfully more constrained and the conversations get harder. Call your relationship manager today. A short call explaining the situation before the bank flags it formally changes the trajectory more than most borrowers realize.
Q2: What's the real difference between a stressed account and an NPA?
A stressed account is where you still negotiate. NPA is where negotiation gets expensive. Stress is a broad term; it covers anything from "the bank is watching this closely" to an SMA-2 account a few weeks from the 90-day threshold. At this stage, restructuring, bridge funding, and OTS conversations are all on the table. Once NPA is formally recorded, you're dealing with recovery teams, SARFAESI notices, and legal timelines that move on their own schedule regardless of what you're trying to sort out. The sooner you address missed payments, the more of that landscape you avoid entirely.
Q3 Can a loan account come back from NPA status?
Yes, regularize all overdue dues, including accrued interest and charges, and the bank can upgrade the account. But the NPA classification stays in your CRILC records for the relevant period, and future lenders will see it. That's not a reason to avoid regularizing; you absolutely should, but it's the clearest argument for catching the early warning signs of missed payments early enough that the formal NPA tag never gets attached in the first place.
Q4 What options exist for MSME borrowers with missed payments who can't immediately regularize?
More than most borrowers expect, especially at the pre-NPA stage. Receivables financing, promoter-backed bridge instruments, loan restructuring with extended moratoriums, and specialist stressed or distressed account funding facilities all exist for businesses where operations are fundamentally sound but the balance sheet is stretched. The further the account slides toward or into NPA, the more limited and expensive these paths become. Acting while the account is still classified as stressed, not yet non-performing, is what keeps the full range of options alive.
Q5 Does the bank tell you when your account has been internally flagged as a stressed account?
Usually not not until they have to. Banks are required to report SMA classifications to RBI's CRILC system, but there's no formal obligation to notify borrowers the moment an account gets placed on internal watch. This is why waiting for the bank to raise the alarm is the wrong strategy. The early warning signs of missed payments show up in your own data overdraft utilization, debtor aging, pre-EMI scrambles well before any formal communication arrives. Reading your own signals is the only early warning system that actually gives you time to act.
Q6 The Window Is Open Until It Isn't
The early warning signs of missed payments don't hide. They accumulate in the overdraft that won't clear, in the vendor you keep on hold for one more week, in the DSCR figure your CFO quietly noted last quarter and decided not to escalate. The businesses that navigate credit stress well aren't the ones with better luck. They're the ones who read the pattern early and moved on it.
The window is open right now for borrowers who catch these signals early enough. Most who wait find out too late what that window was worth.
Q7 Is your account showing early signs of stress?
Credit Curators works with MSME and corporate borrowers to structure funding and resolution strategies before the window closes. Get a confidential assessment today.
 Credit Curators