17 Sep 2026
When Your Loan Goes Red: What A Financial Advisor To Help With Debt Does
Every business owner reading this knows exactly the moment I'm talking about. The EMI just didn't quite work this month. The receivable that was supposed to land by the 2nd but didn't. The bank balance on the 5th that made your stomach drop. And that quiet voice in the back of your head that says, "It'll sort itself next month."
Sometimes it does. But sometimes more often than most, promoters are willing to admit by the time you accept it won't, your loan account has already moved into SMA territory. And a very different set of people at your bank are now tracking your file. That's when getting a financial advisor to help with debt involved stops being a good idea and starts being an urgent one.
This isn't a generic overview. What follows is a stage-by-stage account of what actually happens inside stressed accounts, what the right advisor does at each point, and why timing is the variable that changes everything.
The Key Takeaway
A financial advisor to help with debt isn't a last resort; that's the single biggest misconception in this space. The earlier you bring one in, the more resolution pathways are still on the table. The role of a financial advisor to help with debt is most powerful precisely when the situation still looks manageable, not when it doesn't. At SMA-0, you have real leverage and genuine options. At NPA, you're fighting a much harder battle with far fewer tools.
The difference between those two outcomes is usually just time and the decision to act on it.
Why Timing Is the Whole Ballgame
Let's not dress this up. The most common and most costly mistake stressed borrowers make isn't the debt itself. It's the delay.
India's banking system operates on a defined clock. Under the RBI's Prudential Framework for Resolution of Stressed Assets issued June 7, 2019, lenders are obligated to initiate resolution processes within specific timelines once an account triggers review. The system moves whether you do or not. Silence from a borrower isn't interpreted as patience. It's interpreted as either an inability or disengagement, neither of which helps your negotiating position.
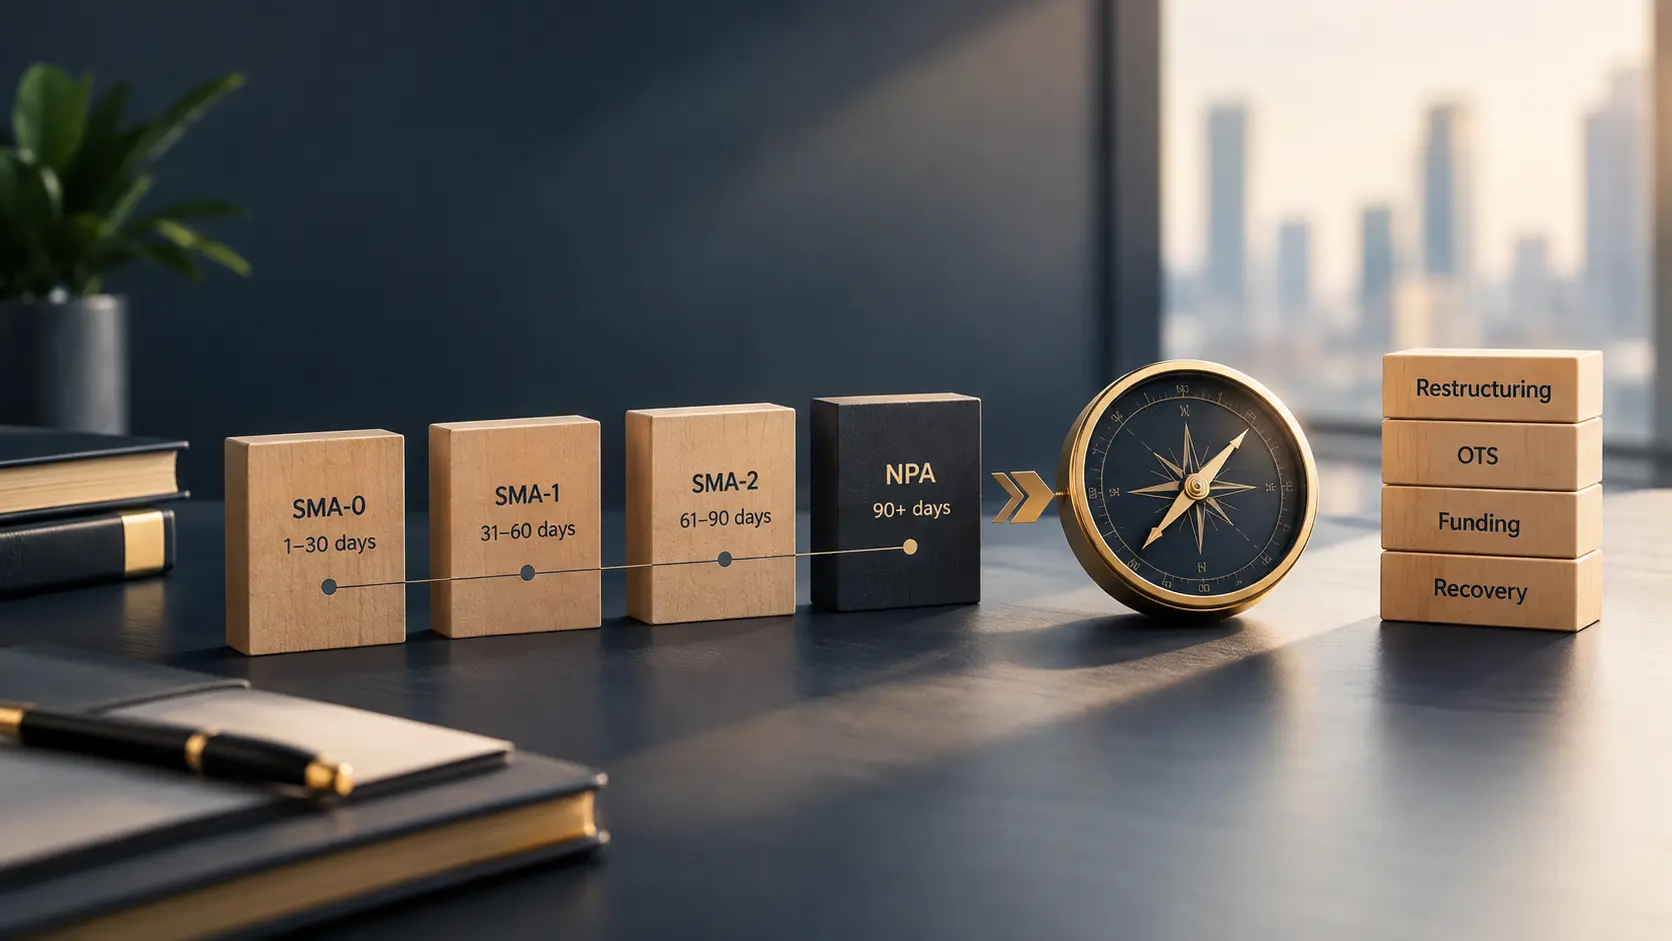
The SMA classifications are straightforward: 1 to 30 days past due puts you at SMA-0. 31 to 60 days, SMA-1. 61 to 90 days, SMA-2. Cross 90 days unpaid, and the account is officially classified as a non-performing asset. Each stage triggers different internal bank processes, and each stage removes at least one resolution option that was available at the stage before.
A financial advisor to help with debt who has worked on both sides of this process understands exactly where those options disappear. And they know how to protect them.
What the Right Advisor Does Stage by Stage
SMA-0: The Window Most People Sleep Through
This is the stage where doing nothing feels most justifiable and where it causes the most damage. The account isn't flagged yet. Your relationship manager is still your primary contact. No notices have landed. Surely it can wait.
It can't. SMA-0 is actually the most valuable moment to engage, because the negotiating room is at its widest. A good financial advisor to help with debt at this stage starts with cash flow forensics, mapping real inflows against actual repayment obligations to identify whether this is a timing problem or a structural one. If it's structural, they start building the case for lender negotiation before the bank builds its own narrative first.
They're also reviewing existing loan covenants for built-in flexibility rescheduling clauses, moratorium provisions, and force majeure language and evaluating whether stressed account funding makes sense to regularize the account while a longer resolution plan is developed.
[Suggested image: Infographic showing SMA-0 → SMA-2 → NPA timeline with resolution options at each stage] ALT text: "Loan stress classification stages from SMA-0 to NPA and resolution options for MSME borrowers Credit Curators"
SMA-1 and SMA-2: When It Gets Serious
By the time an account reaches SMA-1, the bank's stressed assets desk is typically watching. The dynamic with your bank shifts sometimes visibly, sometimes not yet, but it shifts. This is where debt advisory work moves into full restructuring mode.
Here, a restructuring advisor is usually preparing a Techno-Economic Viability (TEV) report, a document that frames your business as fundamentally viable despite the current repayment stress and which lenders actually give weight to when evaluating resolution proposals. Businesses facing repayment stress should also understand the debt restructuring process in India before deciding on their next resolution strategy. Alongside that, they're drafting a Debt Resolution Plan where the repayment schedule is tied credibly to your actual revenue cycle, not to a number that sounds good but falls apart under scrutiny.
If you're in a consortium lending arrangement, this stage gets considerably more complex. Multiple lenders mean multiple approval hierarchies, varying internal risk thresholds, and the very real risk of one dissenting bank derailing a resolution that every other lender has agreed to. An experienced financial advisor to help with debt has usually navigated enough consortium deals to manage that dynamic without letting one dissenting voice derail the whole resolution.
NPA Stage: Legal Intelligence and Capital, Together
At 90-plus DPD, the legal machinery starts. Section 13(2) of the SARFAESI Act brings the demand notice. Section 13(4) brings the threat of possession. DRT proceedings and NCLT filings enter the conversation. This is not the time to be figuring out who to call.
A financial advisor to help with debt at this stage works tightly alongside legal counsel to do three things: negotiate a One-Time Settlement at a quantum the bank's credit committee will actually clear; evaluate whether the IBC resolution route, including the Pre-Packaged Insolvency Resolution Process introduced specifically for MSMEs, creates a cleaner outcome than OTS; and source distressed account funding to execute whichever path makes commercial sense.
What Banks Want: The Part Nobody Talks About
Here's something that surprises most borrowers when they first hear it: banks don't always want your NPA.
Provisioning norms under RBI regulation are punishing for lenders. Classifying an account as NPA means the bank sets aside significant capital against it; it can't deploy anywhere else. That's a real cost on the bank's books, on top of the regulatory scrutiny that comes with a rising NPA ratio.
This creates a genuine, often underutilized alignment between stressed borrower and lender. When a credible resolution exists presented professionally, with supporting documentation, at the right level within the bank, lenders often prefer it to a drawn-out recovery process.
A skilled restructuring advisor positions your case around exactly that. Not as "the borrower asking for a haircut" but as "a viable business presenting a resolution that works commercially for both sides." That positioning shift is worth more than any individual negotiating tactic.
For CFOs and CAs Managing This on Someone Else's Behalf
If you're a finance professional holding the file on a stressed account, whether for your employer or a client, the early-intervention principle applies to you just as directly. Recognizing SMA triggers, escalating them through the right channels, and bringing in a financial advisor to help with debt before the situation hardens are fiduciary decisions, not optional ones.
SIDBI's MSME Pulse reporting at sidbi.in tracks sector-level credit stress patterns across Indian small business lending, worth keeping tabs on if you're advising multiple borrowers. And for legal professionals navigating SARFAESI and IBC proceedings on behalf of corporate defaulters, Bar and Bench remains one of the sharpest sources for NCLT jurisprudence and emerging case law.
FAQs
Q1: Is debt advisory really different from what my CA does, or is it the same thing repackaged?
Genuinely different. Your CA handles compliance, audit, and tax. Debt advisory is a separate discipline built entirely around the lender relationship when it's under strain. The skill set is different; it involves lender-side knowledge, TEV analysis, settlement structuring, and experience with how banks' credit committees actually make decisions. Some CAs do overlap into this territory, and some do it well, but it's not the same practice, and it shouldn't be treated as one.
Q2: What does a restructuring advisor bring to a negotiation that I can't bring myself?
Mostly credibility and institutional knowledge. Banks deal with stressed borrowers constantly. What makes a restructuring advisor's involvement meaningful is that they speak the bank's internal language—they know which desk handles which ticket size, what a credit committee needs to see before approving a haircut, and how to structure a settlement proposal so it doesn't get buried in review cycles. Walking into a bank negotiation without that context usually means either leaving value on the table or pushing too hard in the wrong direction.
Q3: When exactly should I reach out to a financial advisor to help with debt?
Before you think you need to. If you can see a cash flow gap coming, even if you're fairly sure it'll close, that's the moment to have an initial conversation. SMA-0 gives you the most options. Every stage after that removes at least one of them. By the time Section 13(2) arrives, you're not just dealing with a debt problem. You're managing a legal, reputational, and operational one simultaneously.
Q4 Can a restructuring advisor actually negotiate an OTS? How does that work?
Yes, and it's one of the more nuanced things a good advisor does. OTS negotiation isn't just picking a settlement number. It's calibrating the quantum the lender will accept against what the bank's credit committee can justify internally, structuring the payment timeline around the borrower's actual capacity, and making sure the final documentation, the no-dues certificate, and the discharge are clean enough to close the chapter properly. Getting any one of those elements wrong can either kill the deal or produce a settlement that looks like relief but isn't actually executable.
Q5 Is there a funding option if I need capital to execute a settlement or resolution plan?
Yes. Distressed account funding exists precisely for this capital deployed at or after the NPA stage to fund OTS payments, ARC settlements, or execution of an NCLT-approved resolution plan. It's structured differently from regular credit because the borrower profile is different, and the underwriting reflects that. For many businesses, it's the piece that makes an otherwise agreed resolution actually executable rather than just agreed to in principle.
Q6 What if my business is a small MSME? Is debt advisory still relevant for me?
Absolutely. The scale of the loan doesn't determine whether you need professional support; it determines the type and complexity of the resolution framework that applies. The RBI has specific restructuring provisions for MSME borrowers, and the Pre-Packaged Insolvency Resolution Process under the IBC was designed specifically for smaller enterprises. Regardless of ticket size, if there's a bank loan under stress and a business worth saving, debt advisory is relevant.
One Last Thing
The businesses that come out of SMA and NPA situations intact all share the same pattern in hindsight: they stopped treating debt stress as a problem to manage quietly and brought in a financial advisor to help with debt before the situation got away from them.
Choosing the right financial advisor to help with debt is about finding someone who can sit across from your lender and make the case that your business is worth saving. Credit Curators works with MSME owners, promoters, and CFOs across every stage from first stress signal to full NPA resolution. If your account is showing any of the signs discussed here, now is the time to get the right advice. Not next month.
Talk to the Credit Curators team → creditcurators.in
Explore distressed account solutions → creditcurators. in/distressed-account-funding
Follow Credit Curators on LinkedIn for weekly insights on debt resolution, NPA strategy, and MSME credit.



 Credit Curators