24 Aug 2026
NPA Classification In India: What Every Borrower, Promoter & CFO Must Know Before The Clock Runs Out
Most business owners don't hear the phrase NPA classification from their relationship manager. They hear it from someone further down the bank's recovery chain. By that point, weeks — sometimes months — of the most manageable window have already passed.
That's the pattern that repeats across thousands of MSME accounts, SME portfolios, and mid-corporate loan books every year. The account quietly slips through SMA stages. The 90-day mark comes and goes. And what was once a repayment problem becomes a classification problem — with a very different set of rules, a different set of people involved on the bank's side, and a noticeably shorter list of options for the borrower.
Here's the thing though: NPA classification isn't the cliff edge it's made out to be. It's a structured, regulated process. It moves through defined stages. And at each stage — including stages most borrowers assume are too far gone — resolution is still possible. What changes is how much room you have to maneuver.
This guide is about understanding exactly where you are in that process, what each stage actually means for your business, and what decisions need to happen—and when.
Quick Takeaway
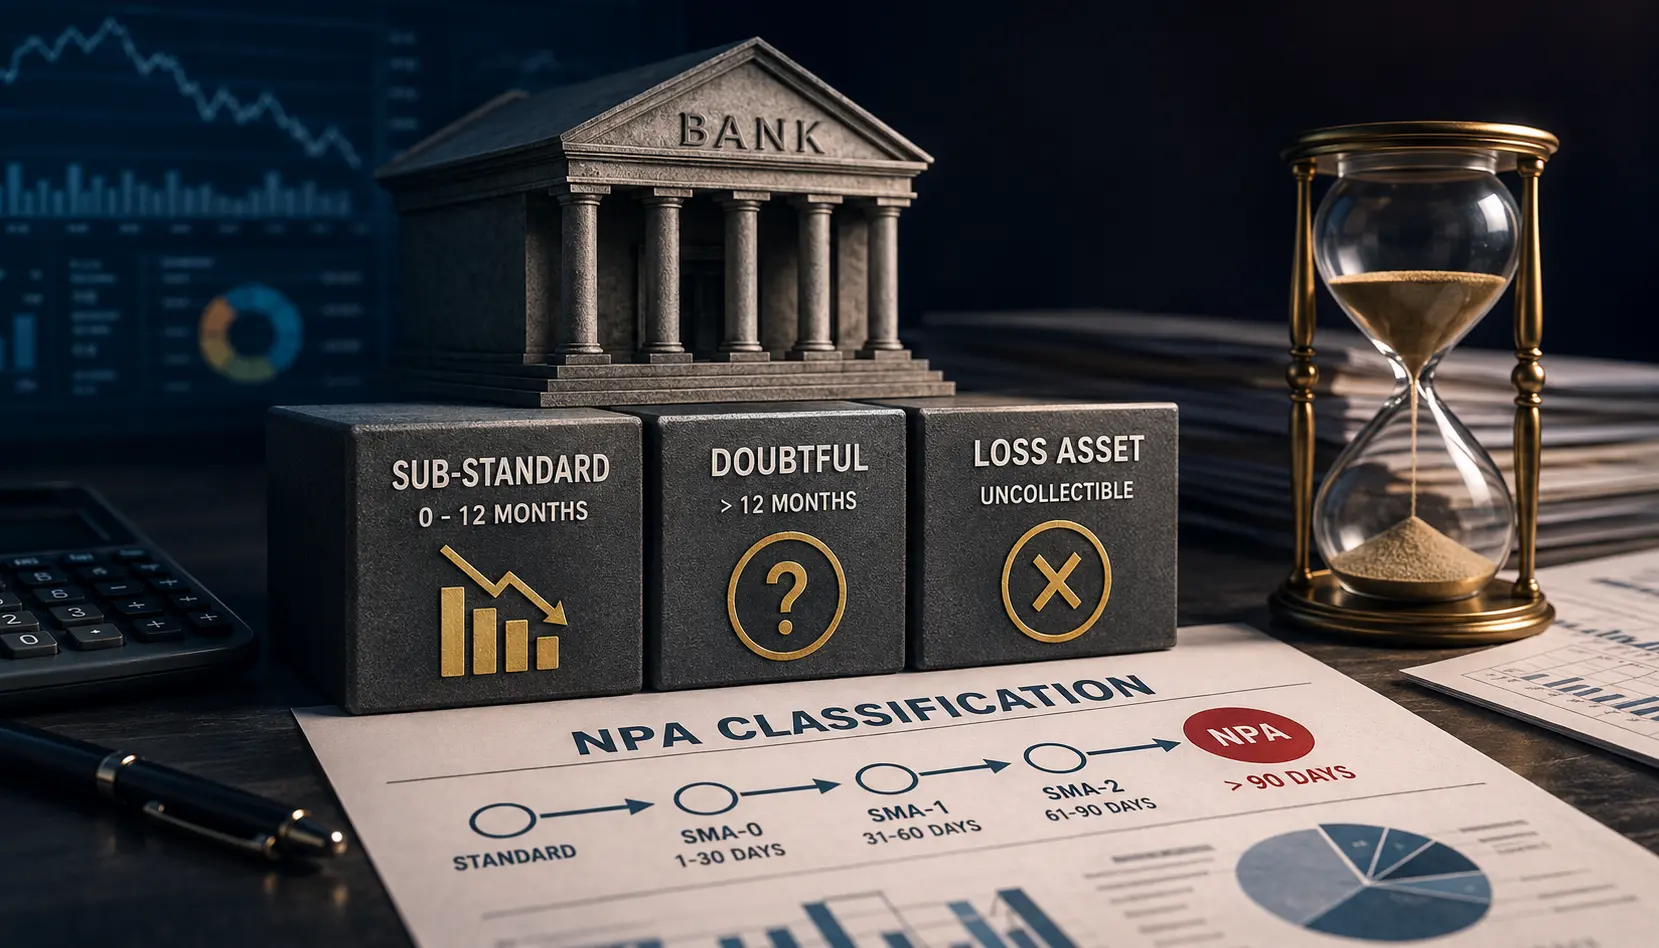
A loan crosses into NPA territory when interest or principal stays overdue for more than 90 consecutive days. After that, NPA classification moves through three stages — Sub-Standard, Doubtful, and Loss Asset — based on how long the account remains non-performing. Each stage tightens what the bank can do and narrows what you can do. But none of them eliminates the possibility of resolution. The earlier you act, the better your outcome.
How the RBI's Classification Framework Actually Works
India's banks don't get to decide for themselves which loans are stressed. The Reserve Bank of India mandates a framework — IRAC norms (Income Recognition and Asset Classification) — that every scheduled commercial bank must follow, uniformly, on an ongoing basis.
This matters for borrowers because it means classification isn't a year-end exercise. Banks are identifying stress in your account continuously. The formal NPA classification that arrives in a notice is usually weeks behind what the bank has already flagged internally.
The framework exists to keep bank balance sheets honest—to make sure institutions are provisioning adequately against potential losses. For the borrower, what it means practically is that once the 90-day overdue threshold is crossed, the NPA label is applied automatically. No discretion. No grace period beyond what's already elapsed.
SMA: The Window Most Borrowers Miss Entirely
Before an account ever reaches NPA classification, it passes through the SMA — Special Mention Account — stages. And this, frankly, is where the real opportunity sits for most borrowers.
SMA-0 is 1 to 30 days overdue. The bank is watching. Your relationship manager may have called. Nothing irreversible has happened.
SMA-1 is 31 to 60 days. Risk teams are involved now alongside the relationship side. Credit committee discussions have started internally.
SMA-2 is 61 to 90 days — the last stretch before the account formally crosses into NPA territory. Recovery teams are in the picture. If the borrower hasn't initiated a conversation by this point, the bank is planning without them.
This SMA window is the most underused part of the entire stressed-asset cycle. Borrowers who engage here — who bring a plan to the table before the classification happens — consistently see better outcomes than those who wait for the bank to dictate terms. If your account is still in SMA, stressed account funding solutions may help prevent it from crossing the line at all.
The Three NPA Categories — What Each One Really Means
For a detailed explanation of Sub-Standard, doubtful, and Loss Assets, read our complete guide to Types of NPA in India
Sub-Standard: The First Twelve Months
A sub-standard asset is any NPA account that's been classified for up to 12 months. Banks must provision 15% on secured advances and 25% on unsecured ones at this stage.
For borrowers, this is still the most workable category. One-time settlement discussions are on the table. Restructuring under the RBI's prudential framework is a real option. Alternative lenders and private credit providers can refinance the exposure and bring the account back to performing status. Banks — even at this stage — generally prefer a structured resolution over a prolonged legal process.
But the window isn't infinite. Acting in month three of sub-standard classification is a very different situation from acting in month eleven. The options don't vanish — they just get more expensive and harder to negotiate.
Doubtful: When the Pressure Escalates
After staying sub-standard for more than 12 months, an account becomes a doubtful asset. Provisioning requirements step up sharply here—from 25% in the first year of doubtful classification to 40% between one and three years to 100% beyond three years for secured advances. Unsecured exposures hit 100% provisioning immediately upon doubtful classification.
This is also where formal enforcement mechanisms become active. SARFAESI — which lets banks take possession of collateral without a court order — is a live tool here. DRT filings become realistic. For larger exposures, NCLT proceedings under the IBC enter the conversation.
Even so, distressed account funding solutions are specifically designed for accounts in this range. Businesses that land here through temporary liquidity stress — rather than fundamental business failure — often still have a viable case to make. It just needs to be made more compellingly than it was at the sub-standard stage.
Loss Asset: What the Name Actually Does and Doesn't Mean
A lost asset is where the bank, its auditors, or the RBI has determined that the loan is effectively uncollectible. Provisioning hits 100%. The exposure is written off on the lender's books.
Here's what many borrowers don't understand: a write-off is an accounting event, not a legal one. The debt doesn't disappear. Recovery continues—either directly by the bank or through assignment to an asset reconstruction company (ARC) or distressed debt buyer.
The counterintuitive part? Structured settlements at the loss asset stage happen more often than people expect. ARCs and distressed investors acquire these accounts at a discount — which means they have commercial room to negotiate a settlement that makes sense for both sides. Special situation funding can be particularly relevant here, especially where the underlying business retains real operational value worth preserving.
The Costs That Don't Show Up on the Balance Sheet
The provisioning percentages get discussed. These don't.
Working capital lines freeze immediately on classification. A business already under stress on its term loan suddenly can't access the credit it needs to run daily operations. The two pressures compound each other fast.
Promoter liability surfaces. If you've given a personal guarantee—and most MSME promoters have—NPA classification on the business loan creates direct personal exposure. SARFAESI notices can be served on you individually. Your personal credit bureau profile takes a hit. Your ability to guarantee other loans or borrow personally is affected.
Cross-default clauses fire. Businesses with multiple banking relationships often find that one lender's NPA classification triggers reviews — and sometimes enforcement — across the entire group's credit portfolio simultaneously.
Can an NPA Classification Actually Be Reversed?
Yes — but clearing the overdue amount is the starting point, not the finish line.
Under RBI's asset classification norms, once the dues are cleared, the account still needs to demonstrate satisfactory repayment behavior over a specified period before the bank can formally upgrade it back to standard. That observation period is there to confirm the resolution is real and not temporary.
For accounts where clearing the full overdue amount isn't immediately possible, restructuring under the RBI's prudential framework—or resolution via the IBC—provides structured legal pathways. The advisory and resolution services at Credit Curators are specifically built for helping borrowers put together proposals that are credible to lenders and executable in practice.
The RBI's Master Direction on IRAC norms is the definitive regulatory text. For any account where IBC proceedings are in view, the IBBI's framework documentation is equally important reading.
Frequently Asked Questions
Q1 My bank just told me I'm at SMA-2. How much time do I actually have?
Not much — and that's the honest answer. SMA-2 means your account is between 61 and 90 days overdue. Once it crosses 90 days without the dues being cleared or a formal restructuring in place, NPA classification kicks in automatically. You're looking at weeks, not months. The conversation with your bank—and with any resolution advisor—needs to happen now, not after the next installment date.
Q2: What are the NPA categories, and does which one I'm in actually change my options?
It changes them significantly. The three NPA categories are Sub-Standard (first 12 months of classification), Doubtful (after 12 months in sub-standard), and Loss Asset (when the bank has provisioned 100% and written the account off). Each stage brings higher provisioning requirements on the bank's side and stronger enforcement tools. From the borrower's side, the earlier the category, the more options remain open and the more negotiating room you have. That's not just a general statement — it shows up concretely in settlement terms, restructuring eligibility, and the bank's appetite for a negotiated outcome.
Q3 The bank mentioned SARFAESI. What does that mean for my property?
SARFAESI gives the bank the legal right to take possession of secured collateral—property, plant, and equipment—without going to court first. It's most commonly invoked during the doubtful stage, though it can technically be triggered earlier. After the bank issues a demand notice, there's a 60-day window before physical possession action can begin. That window is time you can use—for a settlement discussion, a legal challenge, or to arrange alternative funding. Don't sit on it waiting to see what happens next.
Q4 I cleared what I owed. Why hasn't asset classification been reversed?
This is one of the most common frustrations we hear. Paying the overdue amount is necessary—but it doesn't flip the classification switch immediately. The bank is required under RBI norms to observe a satisfactory repayment track record after the overdues are cleared before it can formally upgrade the account. The length of that observation period depends on the category and the bank's internal policies. Keep paying consistently and document everything. The upgrade will follow, but it isn't instant.
Q5 Can NPA classification on my business loan affect me personally?
Yes, and more directly than most promoters realize until it happens. Personal guarantees — which most MSME borrowers have signed — mean the bank's recovery rights extend to you individually, not just the company. Under SARFAESI, personal assets covered by the guarantee can be pursued. Under the IBC, banks can file separate personal guarantee proceedings before the NCLT even while the corporate entity's resolution is ongoing. Your personal credit bureau profile is also affected, which has downstream implications for any personal borrowing or guarantees you might need to provide elsewhere.
Conclusion
NPA classification is a process with rules, stages, and — at every stage — options. The borrowers who navigate it successfully aren't the ones with the cleanest balance sheets or the most lenient banks. They're the ones who understood exactly where they stood and engaged early enough to shape what happened next.
If there's a single takeaway here, it's this: the stage of NPA classification your account is in right now determines which resolution tools are available to you. Don't let more time pass and let the classification determine that for you.
Talk to Credit Curators Before the Window Narrows
Whether you're watching your account approach the 90-day mark or dealing with a classification that's already in place, Credit Curators works with MSME owners, promoters, and CFOs to develop resolution strategies that are realistic for where you actually are.
Explore stressed account funding if you're in the pre-NPA window or distressed account funding if the account is already classified. Reach out directly for a confidential conversation at creditcurators.in/contact.



 Credit Curators