30 Oct 2026
The NPA Recovery Process Explained- What Every Borrower Must Know Before It's Too Late
Most promoters who call us after receiving a bank notice say the same thing; they saw the stress coming months earlier. They just didn't know what to do about it. That's exactly where the NPA recovery process trips borrowers up. It doesn't begin at the bank's notice. It begins the day your account slips into SMA territory, and by the time the formal letter arrives, one of your most valuable windows is already closing.
This is written for MSME owners, promoters, and CFOs. Not a legal summary, but a working map of what actually happens at each stage and where real options still exist.
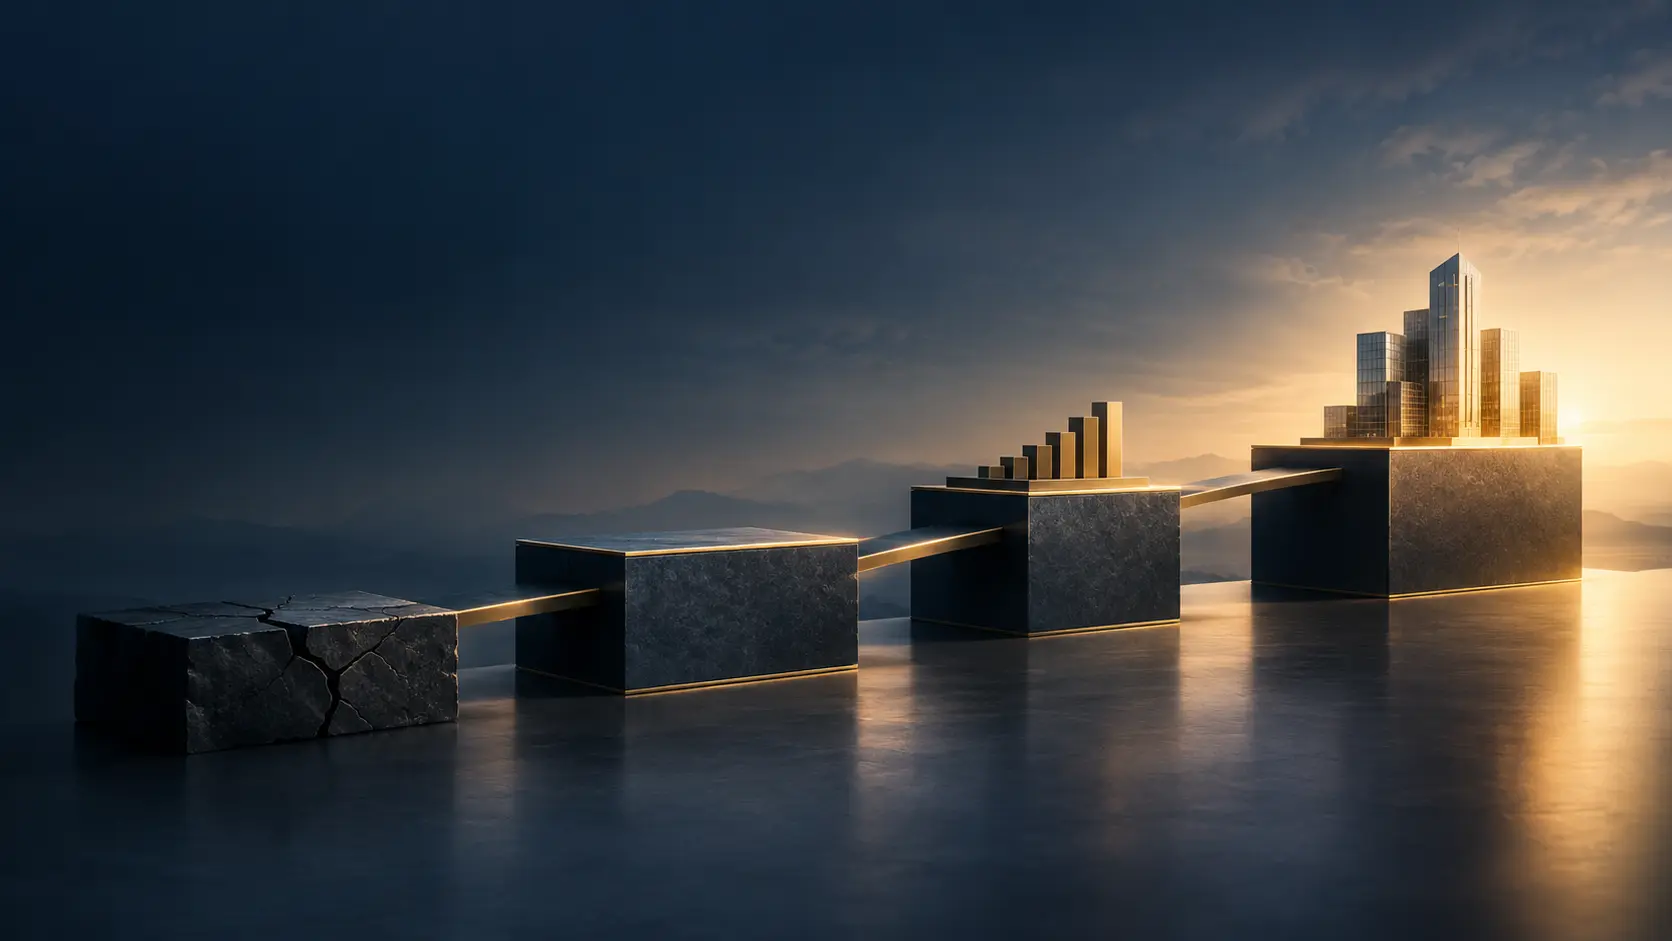
Every stage of the NPA process has a window. The SMA window is the widest. The 13(2) window is still workable. Even post-auction notice, an OTS or DRT stay isn't off the table. What changes at each stage isn't whether options exist; it's what they cost you and how much leverage you have left to use them.
The Stage Banks Hope You Miss: SMA Classification
Banks don't advertise this, but running a SARFAESI auction is genuinely bad for them too. Recovery teams know what distressed asset sales actually fetch and what stays on regulatory books until they do. The economics push lenders toward a quiet early resolution well before any notice goes out. The RBI gives them a monitoring tool that makes finding those accounts early possible.
An overdue loan gets watched in three internal bands before it crosses the 90-day NPA line: one month past due, two months, then 61 to 90 days, where the stressed assets team is most likely already reviewing the file internally. That third band is where the borrower still has a clean, informal entry point. A partial payment or a written restructuring ask at this stage looks completely different to a lender than the same conversation started after a formal notice lands. Most MSME owners miss this window not because they can't use it but because they don't know it exists.
₹4.8L Cr
Gross NPA stock across scheduled commercial banks as of FY2024 is down sharply from a ₹10L Cr peak in FY2018. The declining trend reflects aggressive resolution, but lakhs of active stressed accounts remain at various stages of this process.
What the Law Puts in the Bank's Hands and Where It Leaves Room for You
Three pieces of legislation power India's debt recovery framework. Each one works differently, and each one has a different implication for borrower strategy.
SARFAESI Act, 2002
Secured lenders with an NPA above ₹1 lakh don't need a court hearing before they start moving. That's the practical effect of this 2002 legislation. A demand letter goes out in the first 60 days to respond or clear the overdue. If that window closes with nothing credible from the borrower's side, a possession notice follows. Here's what surprises most first-time recipients: pasting that notice on the gate of a pledged factory or property is legally sufficient to establish control. No physical handover. No keys changing hands. Auction proceedings can begin from that point. Timeline from first letter to sale date under six months in a clean case. Most borrowers expect courts to be involved much earlier. They aren't.
Debt Recovery Tribunals (DRT)
For outstanding amounts above ₹20 lakh, a borrower has a second track. A direct filing at a Debt Recovery Tribunal under the 1993 recovery legislation is where you push back on the process. The window: 45 days from a possession notice to file for a stay on the auction. DRT judges see this motion regularly. What gets traction is a genuine procedural error in the original notice, a funded OTS proposal running in parallel, and real documented repayment capacity. A time-extension application with nothing concrete behind it gets treated accordingly.
Insolvency and Bankruptcy Code (IBC), 2016
The third route available to financial creditors for corporate defaults crossing ₹1 crore runs through the NCLT. A petition to initiate insolvency resolution, if admitted, puts an immediate pause on everything: lawsuits, SARFAESI enforcement, and all active proceedings. A resolution professional appointed by the IBBI takes management while operations keep running. That moratorium is real and can be genuinely useful for a business that needs time to restructure. What it costs is the management seat for as long as the CIRP process runs.
Four Stages. Four Shrinking Windows.
Stage 1: SMA Classification
The widest window, and the one most borrowers don't use because they don't recognize it as a window. A partial payment, a restructuring request, or even a letter that says you know the account is stressed—banks respond to these differently than to silence, because provisioning costs and recovery economics push them toward a deal here rather than enforcement. Once this stage closes, every conversation gets more formal and more expensive.
Stage 2: Section 13(2) Notice (60 Days)
Formal but still negotiable. The 60-day window isn't a countdown to the end; it's the last clean opportunity to present a documented OTS or restructuring proposal before enforcement mechanics take over. Borrowers who respond in writing, even to dispute figures or request an extension, consistently keep more options alive than those who don't. Silence at this stage is a signal to the bank and not a useful one.
Stage 3: Section 13(4) and Symbolic Possession
The bank takes symbolic possession of your secured asset. Physical handover hasn't happened, but auction proceedings can now begin. From receipt of this notice, you have 45 days to approach the DRT. A stay is possible with the right grounds. An OTS offer with a credible funding source can also pause proceedings here, because banks often prefer a settlement to a contested auction with unpredictable bids.
Stage 4: Auction or CIRP
Narrowest window. Not closed. We've seen funded OTS proposals get a hearing within days of a published auction date, sometimes after a first auction failed to attract bids. For corporate accounts, CIRP's moratorium creates time; the IRP takes management. What changes isn't whether a settlement is possible. It's how much you need to bring to the table to move the needle now.
What Borrowers Who Keep Their Businesses Do Differently
Most promoters who've come through this intact say the same thing in hindsight: they wish they'd sent that first letter sooner. Not a legal response, just a few lines. Received your notice dated X. We're disputing the overdue figure for the following reasons. Please allow 30 days for us to submit a proper proposal. That's it. Banks track which accounts are engaging and which aren't. Getting into the first column changes the tone of every subsequent conversation and how seriously the settlement committee takes what you bring them.
The other thing that saves businesses: knowing exactly what SARFAESI can actually touch. The enforcement machinery only moves against assets that were formally pledged as security: a specific plot of land, a factory building, fixed deposits under lien, or registered plant and machinery. If you're walking into negotiations not knowing your own security register, you're negotiating with one eye closed. What's pledged versus what's free determines where your real leverage sits, and most promoters don't have that picture clearly sorted when the notice lands.
For businesses that are generating revenue but short on liquidity right now, distressed account funding exists precisely for this gap, capital structured to clear overdues and regularize an NPA before the SARFAESI enforcement reaches the auction stage.
Three Settlement Routes And Why Most Borrowers Only Try One
Most borrowers know about OTS and nothing else. A bank accepts a discounted lump sum to close the account when full recovery through enforcement looks uncertain. The settlement committee at any public-sector bank runs this against a single benchmark: what would we realistically net at auction, after legal costs and time? A well-provisioned NPA has more settlement room than borrowers typically assume. The proposal needs audited financials, a credible source of funds, and a specific number. An intent to settle is a starting position. It is not a proposal.
What fewer borrowers explore is restructuring, and it's often the better outcome. A tenor extension, a rate reduction, and partial debt-to-equity conversion: if the business can show 18 months of credible forward cash flows, restructuring avoids the CIBIL consequences of a formal settlement and keeps the company intact. Banks don't restructure dead accounts. For businesses that are stressed on liquidity rather than fundamentally broken, this route preserves more than a lump-sum OTS does.
The option getting the least attention involves a change in who you're actually dealing with. Banks routinely offload NPA portfolios to asset reconstruction companies at a fraction of face value, because that's how an ARC's business model works. Once that sale happens, the ARC is your new lender, carrying the same legal powers but a completely different acquisition cost behind the account. Most borrowers in this situation don't realize the account has moved. A CIBIL commercial report check will show you the creditor name changes when an assignment happens. If it has, reach out to the ARC directly, not through the original bank's branch. Their settlement floor isn't the bank's original outstanding. It's what they actually paid for the portfolio. That gap is often more than borrowers assume.
If the capital to execute any of these isn't sitting in your balance sheet right now, stressed account funding can bridge that gap, structured specifically for NPA regularization and OTS settlements, not general lending.
Conclusion
Every stage of the NPA recovery process has a lever. Not the same lever; the one at SMA-2 is cheaper to pull than the one at a possession notice, and the one at auction costs more than either. But none of them have a zero outcome stamped on them in advance. The borrowers we've seen come through this with their business intact almost always did one thing in common: they acted at the earliest stage they found themselves in, not the latest. Whether you're looking at a stressed classification or holding a 13(2) notice right now, what's available today won't be available at the same price next week.
Credit Curators works with MSME owners, promoters, and CFOs at exactly this junction - OTS structuring, bridge capital that stops enforcement, and IBC advisory where the corporate route becomes unavoidable.
Navigating an NPA or Stressed Account Situation?
Credit Curators specializes in distressed and stressed account resolution from OTS structuring to bridge funding to IBC advisory. Connect with our team before your window closes.
Explore Distressed Funding Stressed Account Options
Editorial note: This article has been reviewed by the Credit Curators research desk for accuracy against current RBI circulars, SARFAESI Act provisions, and IBC amendments as of October 2026. It is intended for informational purposes and does not constitute legal or financial advice. For situation-specific guidance, consult a qualified insolvency professional or legal counsel.
Frequently Asked Questions
Q1.) Our relationship manager stopped returning calls after we missed two EMIs. Is that a bad sign?
Ans1.) When a relationship manager stops picking up on a stressed account, the file has usually moved. Not the account - the internal ownership of it. The branch RM is typically out of the decision chain once a stressed assets desk takes over, and that handover can happen quietly at SMA-1, sometimes earlier, well before any notice goes out. The person you dealt with for years may genuinely have no authority over what happens next to your account.
Don't keep calling them. Write directly to the branch head: registered email, short letter, acknowledging the situation and proposing a time to discuss. What shows up in the account file when the settlement committee reviews it later is the written record. The phone calls don't appear anywhere.
Q2.) We missed the 60-day window on a 13(2) notice. Have we lost all our options now?
Ans2.) No but what's on the table now looks different from what was available at 13(2). The bank still has to serve a possession notice before any auction can proceed. From that notice, a 45-day window opens to file for a stay at a Debt Recovery Tribunal. OTS conversations don't close at 13(2) either banks engage post-possession-notice when a credible offer actually lands.
What changes is what 'credible' means. Earlier, genuine intent and a term sheet keeps dialogue alive. At this stage, a settlement committee wants to see funding that actually exists behind the proposal not a number and a willingness to pay later. Come with proof of where the money is coming from. That shifts the conversation.
Q3.) Our books are three years behind on filings. Can we still approach the bank's settlement committee?
Ans3.) The books being delayed doesn't end the OTS conversation - it makes the proposal harder to anchor. Settlement committees at public sector banks run a recovery benchmark: what would we net under enforcement? They build that estimate partly from your financials. Without a credible financial picture, there's no agreed starting point for either side.
A CA preparing even a management-level balance sheet for the past two or three years isn't just cleaning up records that work makes the number you propose defensible. We've seen settlement proposals go through when filings were well behind, but only because a reconstructed financial picture was ready to support the ask. Incomplete books with nothing behind them don't move the committee.
Q4.) The bank mentioned reporting us to CRILC. What does that actually mean for our business?
Ans4.) Not a legal action but it reshapes your entire banking picture, fast. CRILC is the RBI's Central Repository of Information on Large Credits. Any bank with exposure to your company above ₹5 crore can see the stress classification once it goes in. Working capital lines at other lenders get flagged for internal review. If you have consortium lenders, they get alerted together, at the same time.
What this means in practice: a single-lender stress situation can become a multi-lender one in the space of a few weeks, purely from the CRILC entry. Companies that were managing one difficult relationship suddenly find themselves managing four simultaneous reviews because no one had a unified response ready when the reporting happened. That's the risk worth understanding before the entry is made.
Q5.) The notice includes penalties and interest we're disputing. Do we have to accept that figure to negotiate?
Ans5.) Write the objection first, don't wait to build a legal argument. A specific, factual dispute lodged in your written response to the notice is enough to put the question on record. Demand notices sometimes include compounded penal interest calculated in ways you can contest, charges from other accounts, or figures that don't match the account statements you hold.
Raising this isn't obstructive. Every settlement committee at any PSU bank expects borrowers to dispute figures - that's standard. What actually works against you is disputing nothing and then trying to renegotiate the amount later at the table. A written objection on specific line items sometimes shifts the bank's own reference figure when they're benchmarking the OTS. It also shows you're engaging on substance rather than waiting it out.
Q6.) We're a profitable company can a creditor still drag us into insolvency proceedings under IBC?
Ans6.) Yes and this catches more businesses off guard than you'd expect. Profitability and default are distinct conditions under the IBC. A company can be generating revenue while a specific loan stays unpaid: receivables locked, a project that drained the current account, a cash-flow gap that wasn't bridged in time. The lender doesn't care which of those it was.
The threshold for filing an insolvency petition is a default above ₹1 crore not proof your business is failing. A financial creditor has to demonstrate one thing: that you owe money and haven't paid it. That is a low bar, and creditors have used it against operationally viable companies consistently since 2020 when the ₹1 crore threshold was introduced. Being profitable is not a legal defence to a default claim under the IBC.
Q7.) I signed a personal guarantee on our company loan eight years ago. Is that still enforceable today?
Ans 7.) Most likely yes. A guarantee doesn't lapse with age, it runs until the underlying debt is repaid or the guarantee is formally released in writing by the bank. Two things worth a lawyer's eyes before you assume the scope: whether the document covered only the original sanctioned amount or all amounts outstanding, and whether any restructuring or top-up loans since signing fell under the same deed. Standard bank guarantee language typically captures future modifications which means eight years of loan changes may all sit within the original guarantee.
The document itself will tell you what you're actually on the hook for. Read it before assuming anything.
Q8.) Once our NPA is resolved, how do we actually get fresh credit from a new lender?
Ans8.) PSU banks and private lenders don't move on the same timeline here. Public sector banks typically want 24 months of clean repayment post-resolution before they'll seriously consider a fresh facility. Private sector banks and NBFCs are faster - 12 clean months, with the right documentation, often opens a real conversation.
Three things to have ready before approaching anyone: the OTS closure letter from the originating lender, their written confirmation that the account now carries standard classification, and a current-year audited P&L. One thing to check before you apply anywhere: confirm your CIBIL commercial report shows the account as settled or standard not still active NPA. Apply before that update happens and the hard inquiry goes on record, which doesn't help your position. For NPA classification norms, the RBI website is the authoritative reference. For IBC case outcomes and resolution data, the IBBI publishes a searchable database.
 Credit Curators