21 Oct 2026
NPA Resolution In India- What You Need To Do Before The Bank Does It For You
When a business loan starts slipping, most MSME owners do the same thing: buy time. Push through another 30 days. Chase that pending receivable. Call the relationship manager and ask for patience. And then another month is gone.
NPA resolution doesn't start the day a legal notice lands. It starts the day you accept the problem is real. That gap between when stress begins and when you actually move is where recoverable situations quietly become unrecoverable ones.
This guide is built around one idea: acting before the bank does changes what's available to you. Here's what you need to know.
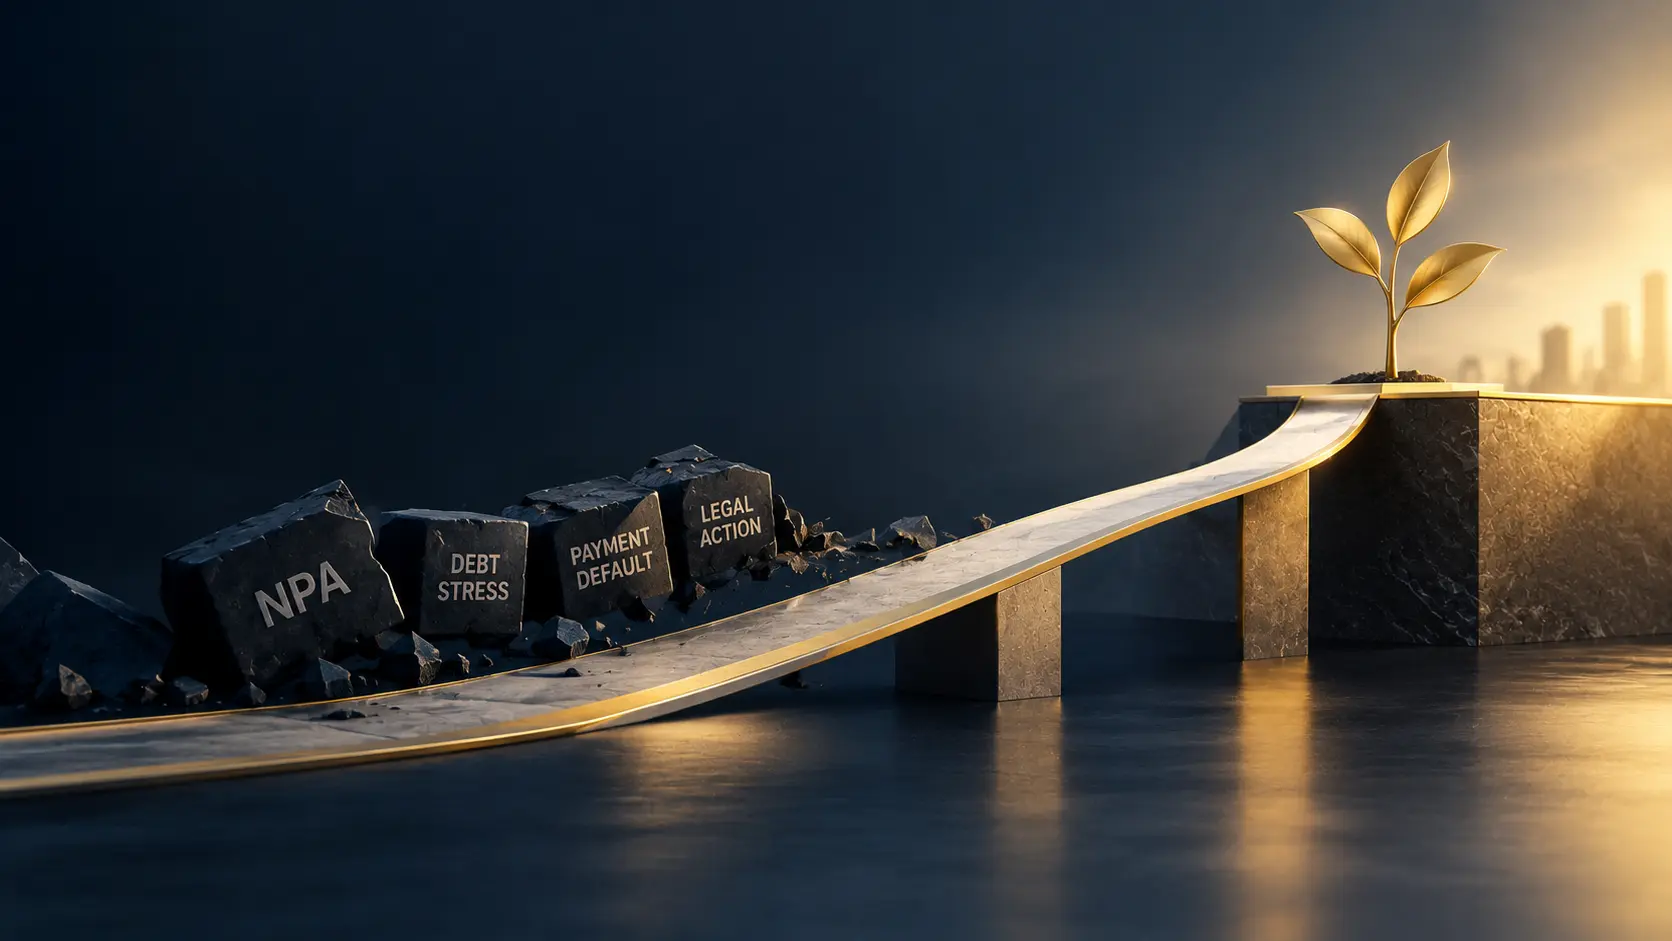
Whether your account is at the SMA stage or already NPA, real options exist: OTS, debt restructuring, IBC, and distressed account funding. Which one fits depends on where your account sits right now. Every week you don't move is leverage you won't get back.
The 90-Day Clock Most Borrowers Misread
Banks don't flip the NPA switch overnight. There's a formal early warning system, Special Mention Accounts, that tracks stress as it builds. Most borrowers don't know it exists or treat it as a technicality.
SMA-0: 1–30 days overdue
Flagged internally at the bank. The borrower is usually unaware. Nothing visible externally yet.
SMA-1: 31–60 days overdue
Internal escalation starts. Relationship managers are pushed to report formally.
SMA-2: 61–90 days is your real negotiating window
The widest opportunity. Banks are still open to structured dialogue here. Act here and you're ahead of the process.
NPA: 90+ days legal mode
Formally non-performing. SARFAESI or IBC proceedings become imminent. Options narrow, but don't disappear.
SMA-2 is where the most paths are still open. A borrower who moves there with a specialist, with documentation, has genuine leverage. Wait for the NPA classification, and you're still in the game, but now you're reacting to the bank's timeline, not yours.
Why Good CFOs Still Miss It
It's not ignorance. It's optimism.
A CFO who's run a solid business for years doesn't naturally walk into a bank meeting to say "we have a problem." There's always a plan: a receivable clearing next week, a facility that's coming through, and a buyer who'll close this month. Sometimes the plan works.
"Every successful NPA resolution we've seen had one thing in common: the borrower moved before the bank forced the conversation."
When it doesn't, two months are gone. The bank's internal file now shows repeated triggers. A conversation that could have been a clean SMA-2 negotiation is now adversarial with a lender that's already escalated well above the branch level. Not impossible. But harder, and with less on offer.
The Five Resolution Mechanisms Honest Breakdown
One-Time Settlement (OTS)
One lump sum. The bank closes the account at a negotiated figure below the outstanding. Banks agree to this more than borrowers expect, especially on smaller MSME accounts where enforcement costs would eat into whatever they recover anyway. But you need capital to fund the payment and a settlement proposal that actually holds up to a credit committee. A weak application gets rejected outright. A well-structured one with a real turnaround narrative, proper documentation, and legal framing moves.
Debt Restructuring Under RBI Framework
This reworks the loan terms instead of settling. Extended tenure, rescheduled interest, principal moratorium, and working capital converted to a term loan are all possible under the RBI Prudential Framework for Resolution of Stressed Assets (June 2019). For accounts with multiple lenders, an inter-creditor agreement coordinates the process. The question banks ask internally: can this business, with restructured debt, generate enough cash to actually service it? Build your answer to that with real projections, not hopeful estimates before any bank meeting.
IBC: Not Just a Threat
Most promoters only hear about IBC when a creditor files. A 180-day Corporate Insolvency Resolution Process begins, managed by a resolution professional. That's not automatically the end. Promoters can participate in Section 29A bars willful defaulters from submitting resolution plans, not every promoter whose loan went NPA. And for complex multi-lender accounts where bilateral talks have stalled, IBC can actually be the cleanest resolution path available. The IBBI website publishes case precedents worth reading before drawing conclusions about what IBC means for a specific situation.
SARFAESI What to Do When the Notice Arrives
Under SARFAESI, lenders can seize and sell secured assets without going to court. Section 13(2) gives you 60 days to respond. Section 13(4) triggers physical possession. Receiving a 13(2) is not the end; it's a mandate to act quickly. Borrowers who file DRT objections and simultaneously push a resolution proposal, both tracks running in parallel, regularly land settlements that weren't possible before the notice arrived. The notice creates urgency. Urgency, handled well, sometimes creates leverage that didn't exist before.
Distressed Account Funding
Most borrowers haven't heard of this. Specialist investors provide capital specifically to resolve NPA accounts, funding an OTS, bridging a restructuring, or buying back the NPA from the bank at a discount. They don't look at your CIBIL score. They look at collateral quality, the underlying business, and whether the resolution math works. For an MSME with clean assets and a temporarily broken cash position, this is often the missing piece. Explore distressed account funding at Credit Curators.
What the Bank Is Actually Evaluating
Not your relationship history. Not your credit score. Three things, in order.
First: is the business genuinely viable with restructured debt? This requires documented evidence and real cash flow projections, not verbal optimism. Banks present these cases to committees; your documentation is what they use to make the argument internally.
Second: Is management credible and cooperative? A promoter who's been unreachable during the stress period starts every negotiation behind. One who communicated proactively throughout even when the news was bad carries goodwill that's difficult to quantify but very real in practice.
Third: Is the collateral clean? For most MSME accounts, mortgaged property is the central variable. Encumbered assets or disputed titles close doors.
For CAs and lawyers handling Section 13(2) or 13(4) notices: The quality of documentation built at the SMA stage and the formal objections filed under SARFAESI directly shape what's achievable in DRT proceedings and any subsequent settlement. Strong early documentation isn't optional; it's what every successful contested resolution is built on.
The Regulatory Picture in 2026
RBI's 2019 Prudential Framework is the foundation. Circulars since have refined timelines, expanded NBFC obligations, and addressed post-COVID account treatment. For MSMEs specifically, dedicated RBI restructuring guidelines offer more flexibility than the standard corporate framework, longer moratoriums, and more lenient viability thresholds. Many borrowers don't know to ask for these. RBI's publications portal is the authoritative source for current circular text.
The direction is consistent: faster resolution, less systemic NPA drag. That works for you if you're moving. It compounds the problem if you're not. Credit curators' stressed account funding solutions are built specifically for borrowers at this crossroads. Follow us on LinkedIn for ongoing regulatory updates.
Frequently Asked Questions
Q1: What's the difference between NPA recovery and NPA resolution, and does it matter?
It matters a lot, actually. Recovery is what happens when you're no longer at the table: the bank auctions your property, files DRT cases, and attaches accounts. You're reacting to their moves. Resolution means you're still part of the conversation, negotiating a path that both sides can live with.
Even when resolution terms are painful, they're almost always better than what happens in pure recovery mode. The goal is to stay in resolution territory as long as possible, which means engaging early, not after enforcement has already started.
Q2 Does my business actually qualify for NPA restructuring?
The real test is whether you can show on paper, with real numbers that your business survives if the debt terms are reworked. Banks aren't looking for perfect businesses. They're looking for ones with a genuine shot if given some breathing room.
MSMEs have an edge most don't know about: RBI's dedicated MSME restructuring guidelines are more lenient than what applies to large corporates, with longer moratoriums and lower viability thresholds. We see clients miss these all the time because nobody told them to ask. If you're assuming the standard corporate framework is your only option, it's worth getting that checked.
Q3: How long does an NPA resolution realistically take?
A single-lender OTS with a solid proposal in three to five months, sometimes less. Multi-lender restructuring through an ICA is six months at best, more often twelve-plus. IBC CIRP runs 180 days statutorily, extendable to 330. And if you're already under a SARFAESI Section 13(2) notice, that 60-day clock is already running.
Don't spend the first two weeks deciding whether to act. That's the part that kills otherwise recoverable situations.
Q4 Can I keep the business running while all this is happening?
Yes, and you should. A business that's still generating cash flow gives you infinitely more to negotiate with than a shut-down operation. Banks, distressed investors, and resolution professionals all know this. The moment operations stop, everyone's calculus shifts toward enforcement.
Under SARFAESI you keep management control until Section 13(4), which is physical possession, not the 13(2) notice. Under IBC CIRP, a resolution professional steps in, but operations can and should continue. Keep the lights on wherever financially possible.
Q5 The bank sold my NPA to an ARC. Is that worse for me?
Not automatically. ARCs exist specifically for resolution; that's their mandate. They're not under the same regulatory pressure as a bank to clean their balance sheet on the bank's timeline. That often means more room to negotiate a realistic settlement than you had with the original lender.
We've seen borrowers get better OTS terms from an ARC than they were ever offered by the bank. Engage early, come with a real proposal, and don't assume the transfer closed the window. Sometimes it opened a new one.
Q6 Does Section 29A of IBC mean the promoter can't participate in the CIRP at all?
No Section 29A bars willful defaulters from submitting resolution plans. That's a specific legal classification, not the same thing as being a promoter whose loan went NPA. NCLT and NCLAT have clarified the boundaries of Section 29A considerably since it was amended, and the bar is narrower than most promoters assume.
If you're uncertain whether it applies to your situation, you need IBC-specialist counsel not a generalist before drawing conclusions. Don't let an assumption about 29A take an option off the table before you've actually checked.
One Last Thing
Every account we've seen resolve well had one thing in common the borrower moved before the bank forced the conversation. Before the escalation. Before the legal notice. Before it became purely an enforcement exercise on the lender's terms.
NPA resolution is a sequence of decisions. The right mechanism, the right timing, the right documentation, the right advisors. Get ahead of it and the options are real. Wait and you're responding to someone else's agenda with whatever's left.
Business Standard's banking coverage is worth following for ongoing regulatory changes in this space.
Understand Your Options Before the Window Narrows
Whether your account is at SMA stage or already classified NPA, Credit Curators brings advisory depth and access to distressed funding built for exactly this moment.
 Credit Curators