22 Sep 2026
Is Your Loan Account Becoming A Stressed Asset Here's What Banks Know That You Don't
There's a phone call most MSME owners come to dread. It starts politely with your relationship manager, the one you've known for years, wanting to schedule a catch-up. Measured tone. Careful phrasing. In banking language, that call carries a specific meaning. Your loan account has crossed a line, and the lender already knows more about your position than you do.
Classification doesn't wait for you to notice something is wrong. That's the part nobody says clearly. Banks run internal watch lists, credit reviews, and regulatory checklists well before a SARFAESI notice lands at your door. By the time that polite call comes in, your account may already be two stages deep, flagged, and escalated, sometimes visible to every lender in the country.
The financial difficulty itself rarely costs borrowers the most. What costs them is the time that passes between when the bank started watching and when the borrower finally started acting. That gap is what this piece is about.
Key Takeaway
A loan account qualifies as a stressed asset across SMA-0, SMA-1, SMA-2, and NPA stages. The first 60 days, the SMA window is where your leverage sits highest. Restructuring, OTS, and specialized bridge funding are all accessible here. After NPA classification, those same options don't disappear, but the environment shifts around them. Timing is the variable that most determines what outcome is possible.
What Qualifies as a Stressed Asset, and Why the SMA Stages Matter More Than You Think
Before a loan account becomes a formal NPA, it moves through the Special Mention Account system. To understand these early warning stages in more detail, read our guide on the [3 types of stress in loan accounts]. Most borrowers assume they'll recognize when their account is in serious trouble. The classification process doesn't share that assumption. Under the RBI's Prudential Framework for Resolution of Stressed Assets (2019), any credit facility where repayment is under genuine pressure qualifies as a stressed asset pre-NPA and post-NPA alike. Early identification isn't optional for lenders; it's a regulatory requirement.
Before a loan account becomes a formal NPA, it moves through the Special Mention Account system. Most borrowers have never heard of SMA until they're already inside it. They should know it earlier.
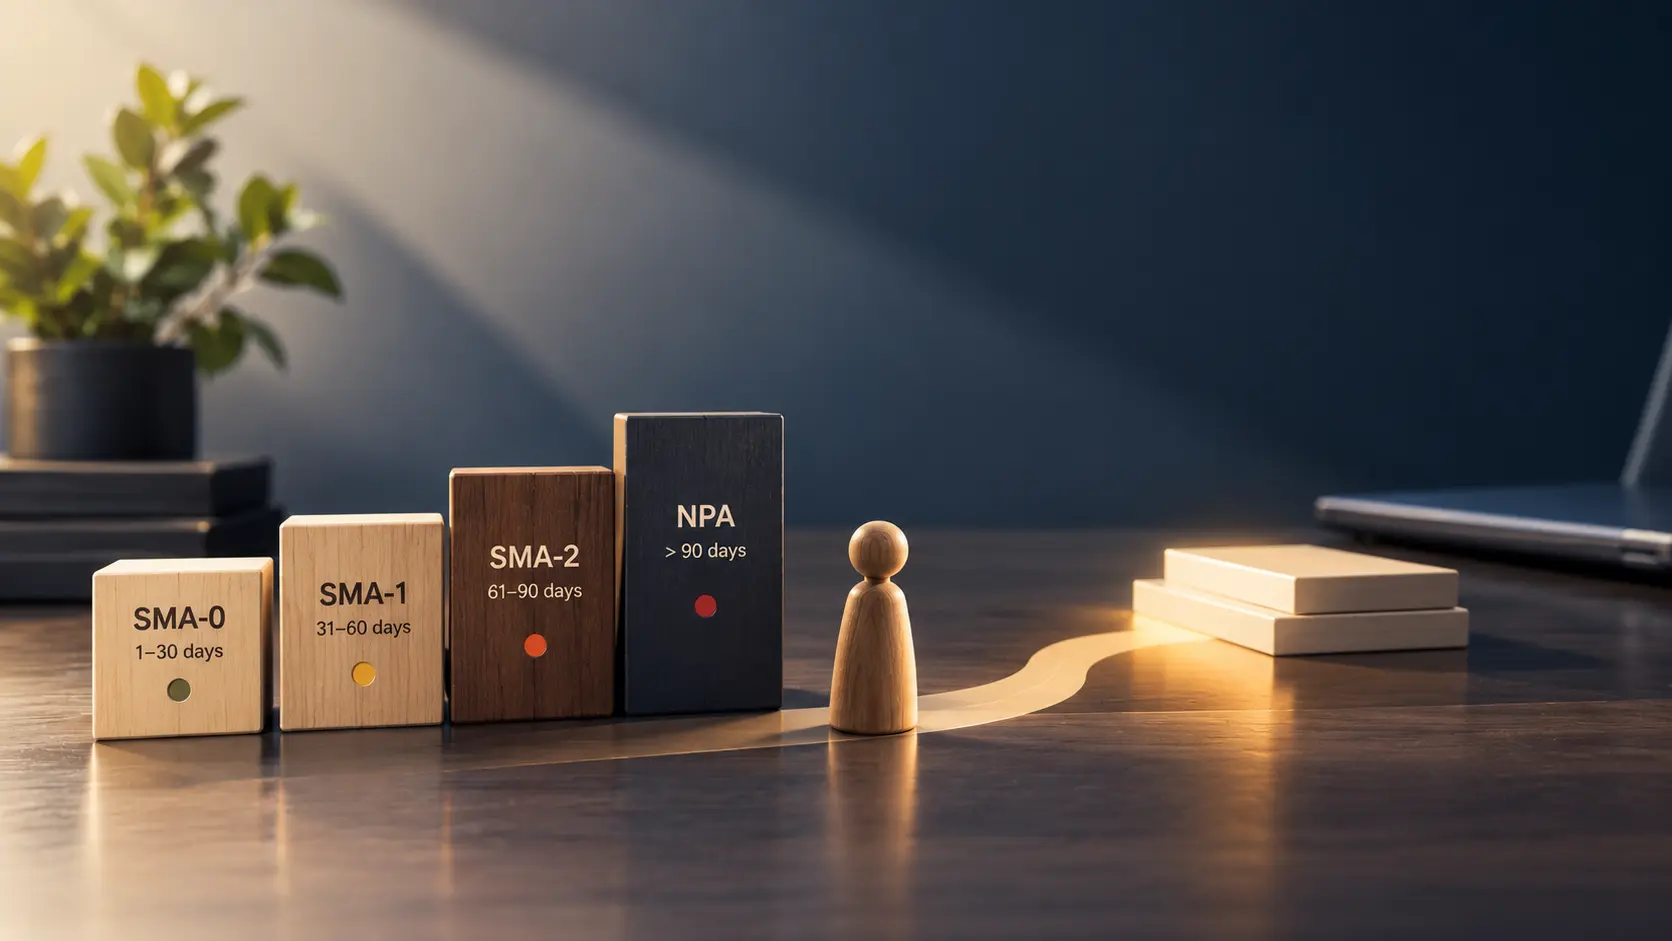
SMA-0
1–30 days overdue. You almost certainly don't know this flag has been applied. The account has entered an internal watchlist. Your RM has received a quiet nudge to engage.
SMA-1
31–60 days overdue. Credit review escalation above the RM level is now standard. The account is being actively discussed. Informal resolution conversations are becoming formal internal ones.
SMA-2
61–90 days overdue. Mandatory CRILC reporting fires here. Every major lender in India can now see your account's status. A private difficulty becomes a system-wide signal often before the borrower knows it has happened.
NPA
Beyond 90 days. Formal non-performing classification. Bank provisioning kicks in. Recovery tools SARFAESI, DRT, and NCLT become available to the lender. The borrower's choices narrow sharply.
Engaging at SMA-0 or SMA-1 means negotiating while options are still open. SMA-2 or NPA means working with a narrowed set. That gap is not marginal for many promoters; it's the difference between retaining operational control and losing the ability to shape what happens next.
What the Bank Is Actually Doing While You're Hoping Things Improve
Something lenders don't tend to say plainly: they're under pressure too. Every unresolved NPA on a bank's books requires provisioning funds set aside against a probable loss, and that provisioning hits profitability directly. Public sector banks face quarterly scrutiny on NPA ratios at a board level. Their own performance metrics are tied to those numbers.
At the SMA stage, the bank isn't waiting to dispatch notices. There's internal motivation to find resolution. A borrower who initiates that conversation with realistic financial data, a credible preliminary proposal, and proper advisory backing walks into a different room entirely from one who's stopped returning calls.
Silence is not a neutral choice. In most cases, it accelerates the internal escalation that makes informal resolution harder. Going dark doesn't buy time; it spends it.
Banks run institutional processes. But the people inside those processes respond to preparation and good faith. That's leverage most borrowers don't realize they have until they've already lost it.
A Scenario Worth Reading Carefully
Take a mid-size auto ancillary manufacturer, Mehta Precision Parts. Six months of supply chain disruption. Margins compressed, receivables slowing, and two EMIs missed back-to-back. By the time the promoter sat down with an advisor, the account had reached SMA-2.
Three routes were still open: a formal restructuring proposal to the lender, bridge financing through a stressed account funding arrangement to regularize quickly, or moving toward IBC proceedings. They chose the second route. The account was regularized in 45 days. Operational control stayed with the promoter. The bank cleared a provisioning burden it had been carrying.
Another 30 days of inaction and the account would have crossed into NPA. The same outcome would have been considerably harder to engineer from that position. The window was there. They used it.
Resolution Options That Are Actually Available to You
One-Time Settlement
PSU lenders in particular will consider OTS proposals for stressed assets near or at the NPA stage, especially when legal recovery looks slow. But this isn't just about naming a number. Understanding what the bank has already provisioned, what their realistic recovery expectation is, and how a proposal navigates their internal approval structure—that preparation is what separates an accepted OTS from a conversation that goes nowhere.
Debt Restructuring
For accounts with a viable business underneath them, restructuring moratoriums, rescheduled principal, and working capital converted to term debt can restore performing status without escalating to legal proceedings. Banks run this through a techno-economic viability assessment. SIDBI's published frameworks for MSME credit support offer useful context for borrowers exploring this route: sidbi.in.
Stressed Account Funding
Most borrowers don't know this option exists. Specialist NBFCs and advisory firms provide structured bridge financing designed to bring a stressed account current before it crosses into NPA. The borrower regularizes the account, restores lender standing, and shifts the negotiation from default to compliance. The value of this option reduces with every week of delay. It is genuinely time-sensitive.
Distressed Account Funding and IBC
When informal resolution hasn't worked and the debt is large, the Insolvency and Bankruptcy Code provides structure. A well-run IBC process, with an experienced resolution professional and credible legal support, can produce outcomes considerably above liquidation value, particularly for businesses with real underlying assets. For borrowers considering distressed account funding as a bridge into an IBC plan, the structure and timing of that financing is not a secondary detail. It often determines whether the resolution plan holds together at all.
What Borrowers Who Navigate This Well Actually Do
What the promoters and CFOs who come through this with good outcomes tend to share isn't exceptional resources. It's timing and a willingness to engage before the situation has forced their hand.
They make the first call while options are still genuinely open. Not after a notice arrives. Not after CRILC reporting has already happened. Earlier when the first signs appear. A payment looking uncertain. Receivables aging in a way that's making the CFO uncomfortable. That's the right trigger.
They also build teams with real resolution experience. A CA who understands banking law, an advisor who has sat in actual lender meetings, and a specialist firm that knows what a credible proposal looks like from the lender's side. That combination changes outcomes in concrete ways, not theoretical ones.
And they stay in contact with their lender, even when those conversations are difficult. Banks have processes. The people inside those processes respond differently to a borrower who shows up with a preliminary plan than to one who has gone silent. That difference shows up in how internal credit reviews are written and what they recommend.
Frequently Asked Questions
What is a stressed asset?
Your loan is in trouble; the bank has a formal classification for it, and so does the RBI. Any credit facility where repayment is under genuine strain, whether already overdue or trending that way, falls inside this category. It runs from early SMA classification all the way to full NPA status. Most borrowers find out where they sit on that spectrum only once they're further along it than they'd have liked.
What's the difference between a stressed asset and a stressed account?
Two framings of the same problem. "Stressed asset" refers to the loan on the bank's books and the credit facility under pressure. "Stressed account" refers to your specific relationship with that lender carrying the same strain. In most professional contexts, regulatory language, advisory conversations, and lender meetings are all used interchangeably. Don't get hung up on the distinction when the priority is resolving the situation.
What does SMA actually mean, and why should I care?
SMA stands for Special Mention Account, the classification that sits between a healthy loan and a formal NPA. Three stages: SMA-0 is 1 to 30 days overdue, SMA-1 is 31 to 60, and SMA-2 is 61 to 90. The part most borrowers don't know until it's already happened to them: SMA-2 triggers mandatory reporting to CRILC, the RBI's central credit registry. Once that report is filed, every major lender in India sees your account's status. A private difficulty becomes a visible signal across the system. Acting before SMA-2 while things are still between you and one lender is almost always the stronger position to be in.
Can a stressed asset be resolved without going to NCLT?
Yes, and for most MSME borrowers, that's the right outcome to aim for. NCLT is adversarial, expensive, and rarely fast. A structured OTS, a restructuring plan the bank can actually approve, or bridge financing that regularizes the account—any of these can achieve clean resolution without a tribunal getting involved. The requirement is timing. At the SMA stage, these routes are genuinely accessible. After NPA classification and formal notices, the same options are still there, but the environment around them has changed.
What actually happens the moment my account is classified as NPA?
The bank provisions against it set aside funds; it's treating it as a probable loss, which hits their profitability. That's also partly why lenders are more motivated to resolve NPAs than borrowers sometimes realize. On your side: CRILC flags your profile across lenders, and formal recovery tools become available, such as SARFAESI possession orders, DRT filings, and NCLT applications. Pathways still exist at this stage. OTS, ARC-led buyouts, and IBC resolution plans are all live. But the conversation has shifted from restructuring to recovery. That's a different dynamic, and it changes what's achievable.
Is there actual funding available for a stressed account?
More MSME owners have used this route than most people realize. Specialist NBFCs offer bridge-to-regularization financing structured specifically to bring a stressed account current before NPA kicks in. The account gets regularized, your standing with the lender is restored, and the conversation resets from default to compliance. Whether it's right for your situation depends on the size of the exposure and how far the account has slipped. On how regularization affects your broader credit profile, TransUnion CIBIL's resources at cibil.com are worth a look.
When should I actually pick up the phone and call someone?
Before you're certain you need to. Genuinely. The borrowers who come out of financial stress with the best outcomes are almost always the ones who engaged while they still had leverage, not after the notices arrived. If the next payment looks uncertain, if receivables are aging in a way that's making you uncomfortable, those are the right moments. Not next month. If reading this piece made you think about your own account, that's probably the signal.
The Bottom Line
Financial difficulty in a business isn't a character flaw. It's a cash flow reality that serious companies face in adverse cycles. The difference between borrowers who come through it on their own terms and those who don't is almost never the severity of the initial problem. It's how quickly they understood their position and what they did while they still had time to act on it.
Stressed assets are manageable. But the window for managing them well is time-bound, and it closes faster than most people expect. Whether your account is at the SMA stage or has already crossed into NPA, the first step is always the same: understand where you actually stand.
Your Account Is Under Pressure. Let's Talk Before the Window Narrows.
Credit Curators works with MSME owners, promoters, and CFOs across India to map out realistic resolution strategies from structured funding to OTS negotiation and beyond.
 Credit Curators